The Triangular Arbitrage & Cross-Currency Routing Engine: Bellman-Ford Negative Cycle Detection, Fee Hurdle Math, and Sub-Millisecond Multi-Leg Execution
In high-frequency quantitative trading, spatial cross-venue arbitrage (buying Bitcoin on Exchange A and selling on Exchange B) faces substantial bottlenecks: asset transfer delays, exchange withdrawal latency, and counterparty capital lockups. To achieve risk-neutral spread capture with zero transfer latency, institutional algorithms deploy Intra-Exchange Cross-Currency Triangular Arbitrage.
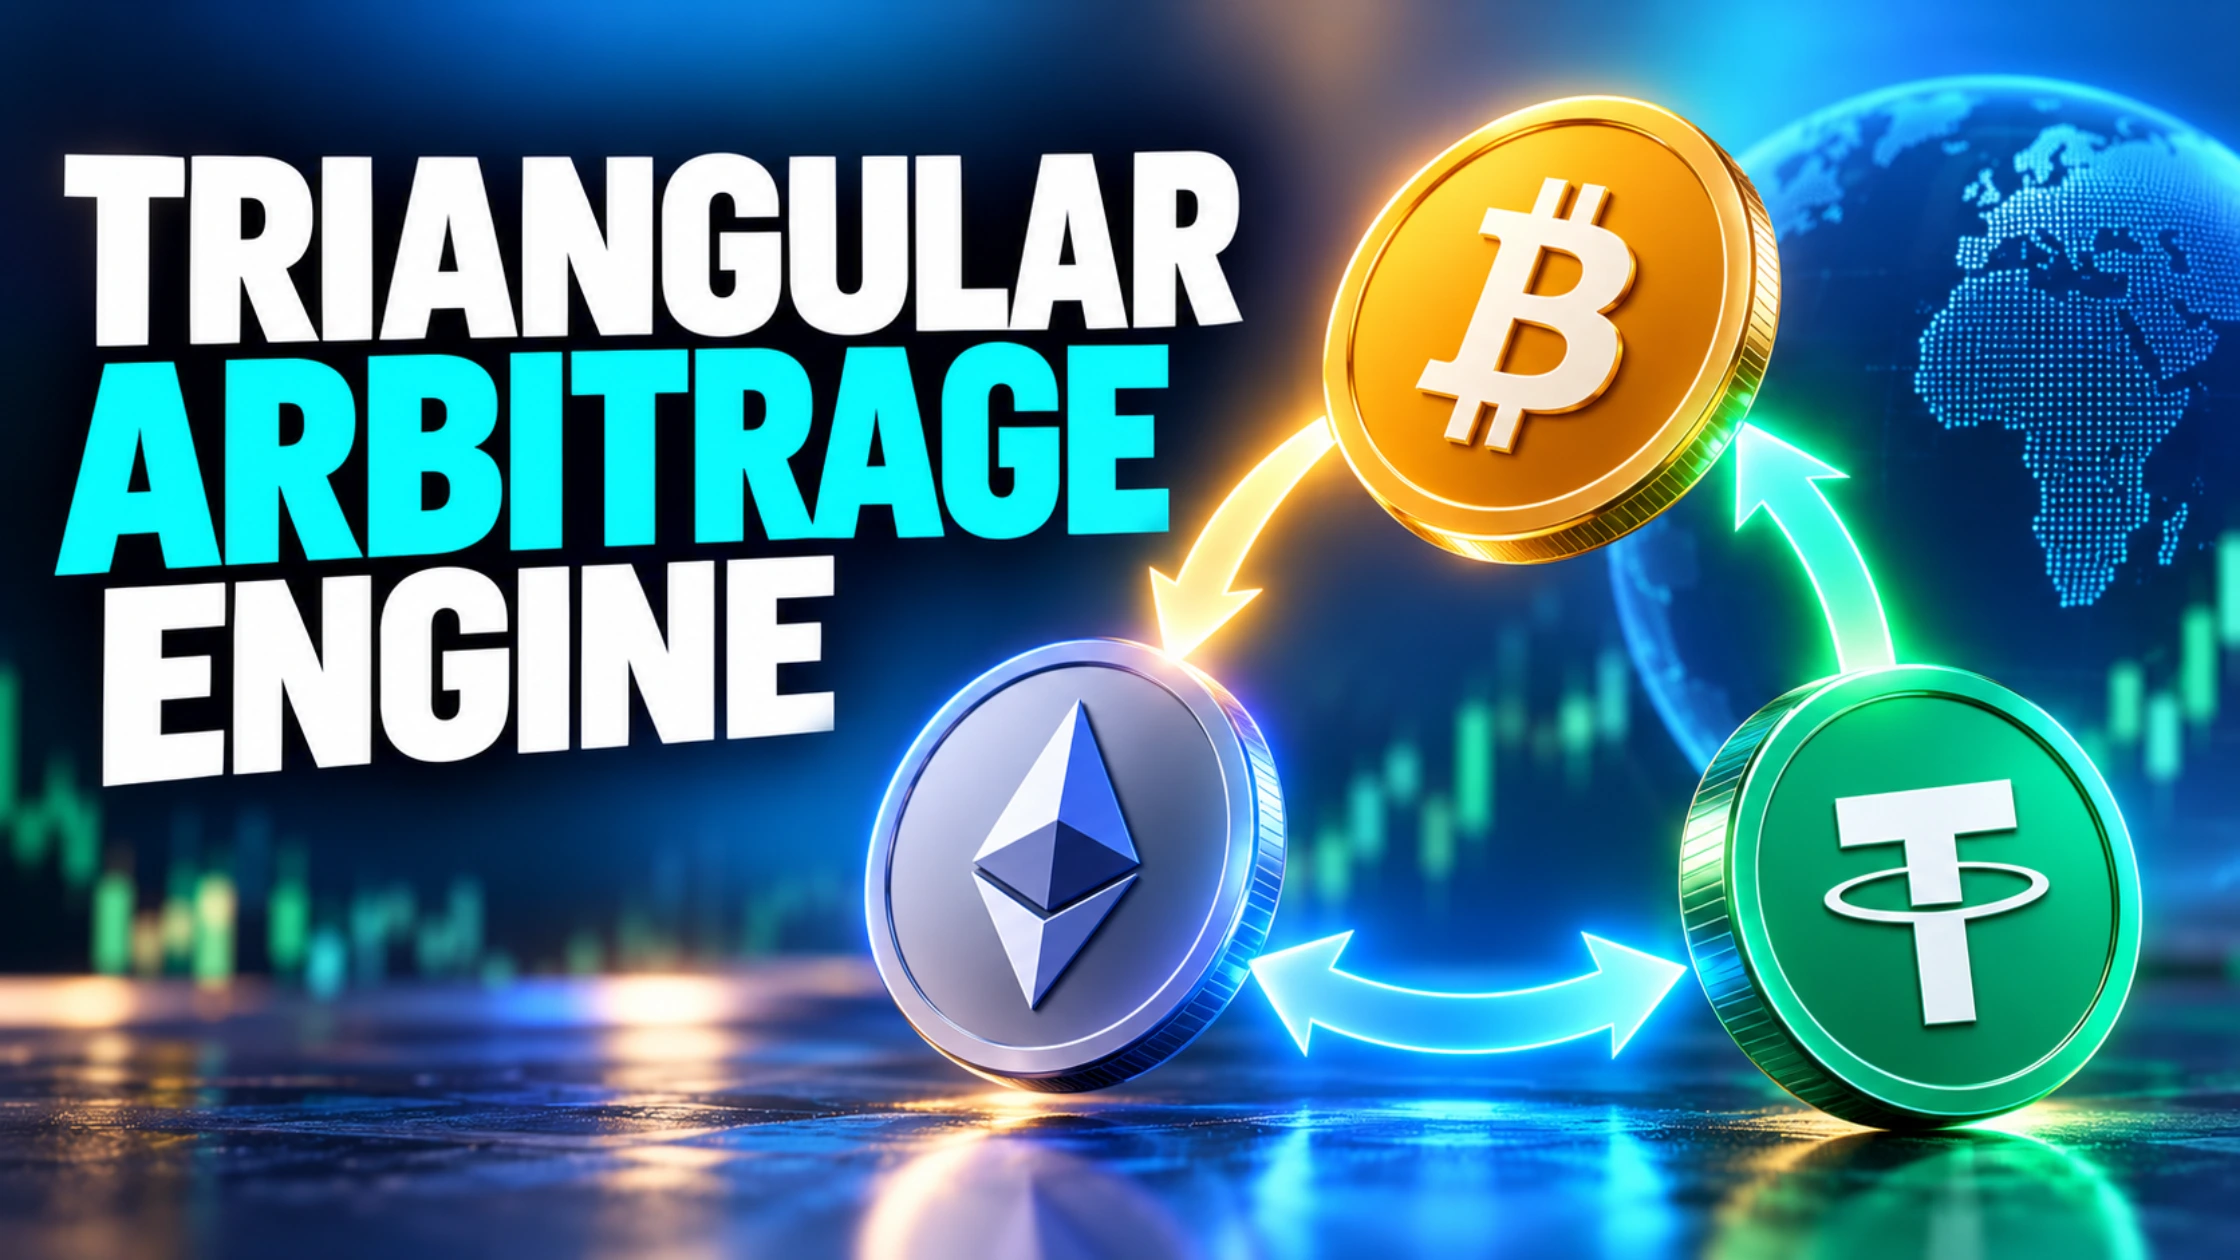
Triangular arbitrage exploits pricing inconsistencies that emerge between three interconnected trading pairs listed on the same clearing order book (for instance: $\text{USDT} \to \text{BTC} \to \text{ETH} \to \text{USDT}$). Because order execution occurs instantly through localized internal matching engines, assets never leave the exchange. However, extracting profitable alpha from triangular loops requires overcoming three formidable hurdles: three compounding tiers of taker fee drag, order book bid-ask queue depth, and sub-millisecond execution decay. In this quantitative guide, we deconstruct the algorithmic graph theory, Bellman-Ford negative-cycle detection models, and fee-hurdle calculus that institutional trading desks use to exploit multi-leg currency triangles.
1. Deconstructing Cross-Currency Graphs & Negative Log Cycle Detection
To identify pricing discrepancies across hundreds of simultaneous crypto trading pairs in real time, high-frequency algorithms do not run simple multiplication checks. Instead, they model the entire exchange order book as a Directed Weighted Graph:
In standard exchange quotation, a triangular arbitrage exists if the product of the three exchange rates along a closed loop exceeds unity after accounting for transaction fees ($f$):
$$R_{\text{cycle}} = \left( \frac{1}{P_{A \to B}} \right) \cdot \left( \frac{1}{P_{B \to C}} \right) \cdot P_{C \to A} \cdot (1 - f)^3 > 1.0$$
Because running repeated matrix multiplications across hundreds of currency pairs is computationally expensive and slow, quantitative engines transform exchange rates into additive weights using negative logarithms. By taking $w_{i \to j} = -\ln(R_{i \to j} \cdot (1 - f))$, finding an arbitrage opportunity transforms into finding a Negative Cycle in a Directed Graph using the classical Bellman-Ford Algorithm:
The Bellman-Ford Negative Cycle Formulation
$$\text{Edge Weight: } w(u, v) = -\ln\left( \text{ExchangeRate}(u \to v) \cdot (1 - f) \right)$$
$$\text{Arbitrage Condition: } \sum_{e \in \text{Cycle}} w(e) < 0 \iff \prod_{e \in \text{Cycle}} R_e \cdot (1 - f) > 1.0$$
Where $u$ and $v$ represent base and quote currency vertices, $R$ is the executable top-of-book price (Ask for buying, Bid for selling), and $f$ is the exchange taker fee percentage. If the sum of edge weights across a closed 3-node cycle is strictly negative, a mathematically guaranteed riskless arbitrage exists before execution latency decay.
2. Interactive Triangular Arbitrage & Fee Hurdle Simulator
Use our quantitative triangular arbitrage simulator below to model a 3-leg currency loop (USDT $\to$ BTC $\to$ ETH $\to$ USDT). Adjust capital allocation, spot prices, cross-rate exchange quotes, exchange fee tiers, and latency decay to calculate synthetic cross-rates, fee drag, net cycle profit, and annualized Sharpe potential.
3. The High-Frequency Triangular Execution Blueprint
Executing triangular arbitrage successfully in live crypto markets requires co-located sub-millisecond API infrastructure, order book queue mapping, and strict treasury segregation. Follow this 4-step framework:
Establish high-speed WebSocket connections to premier spot clearing order books including Bybit (Code: 46164), OKX (Code: 2136301), Binance (Code: CPA_00SXKU7IO9), or Kraken. Stream raw order updates to construct in-memory Directed Adjacency Matrices.
Implement compiled low-latency algorithms (in Rust, C++, or Go) that transform exchange prices into negative logarithmic weights. When a cycle weight drops beneath the fee hurdle ($-\sum \ln(R_i) > 3 \cdot \ln(1 - f)$), fire concurrent Immediate-or-Cancel (IOC) or Fill-or-Kill (FOK) batch order bundles across all three legs simultaneously.
Connect automated algorithmic execution software like Coinrule, Cryptohopper, or 3Commas to execute high-volume multi-pair routing on high-depth spot markets like KuCoin (Code: CX8QMK4M), Bitget, MEXC (Code: 16yJL), or Gate.io (Code: UgUVAVoJ).
Because high-frequency triangular bots require automated API keys with trading permissions, isolate your main treasury collateral and realized profits from exchange platforms. Routinely sweep profits into air-gapped hardware cold storage provided by Ledger or OneKey (Code: 46Z9TD).
4. Triangular Arbitrage & Cross-Currency Analytics Stack
To detect sub-second cross-pair dislocations, monitor fee hurdles, and track multi-leg portfolio cost basis, integrate these professional quantitative tools into your workflow:
- Cross-Exchange & Triangular Spread Scanners: Scan live cross-pair pricing anomalies and multi-currency spread matrices with ArbitrageScanner or ASCN AI.
- Multi-Chain Non-Custodial Cross-Asset Bridges: Rebalance treasury capital between Layer-1 and Layer-2 execution venues using deBridge. For instant, non-custodial swaps without account registration, use SideShift or ChangeNOW.
- Institutional Derivatives & Options Hedging Venues: Hedge intermediate directional risk on deep derivative hubs like Deribit (Code: 5969.4030), Aevo, or Drift.
- Institutional Options Flow & Volatility Term Structures: Track implied vs. realized volatility surfaces to calibrate triangular execution velocity using Unusual Whales.
- Advanced Technical & Multi-Pair Charting Terminals: Map synthetic cross-rates against direct pair channels using TradingView or Coinigy.
- Multi-Chain Tax & High-Frequency Turnover Accounting: Track multi-thousand trade turnover logs and realized arbitrage gains with CoinStats or Koinly.