Perpetual Oracle Basis Risk Index 2027: When Mark Price and Spot Price Diverge
The DN Perpetual Oracle Basis Risk Index measures gaps between spot, oracle, index, mark and liquidation prices across Hyperliquid, GMX, dYdX and gTrade.
Why You Can Get Liquidated Before Spot Hits Your Liquidation Price
Data reviewed: 10 September 2026
Methodology: DN-POBRI v1.0
Affiliate disclosure: Decentralised News may receive compensation when eligible users use certain partner links. Commercial relationships do not determine benchmark inclusion, methodology, measurements or conclusions.
The Signal
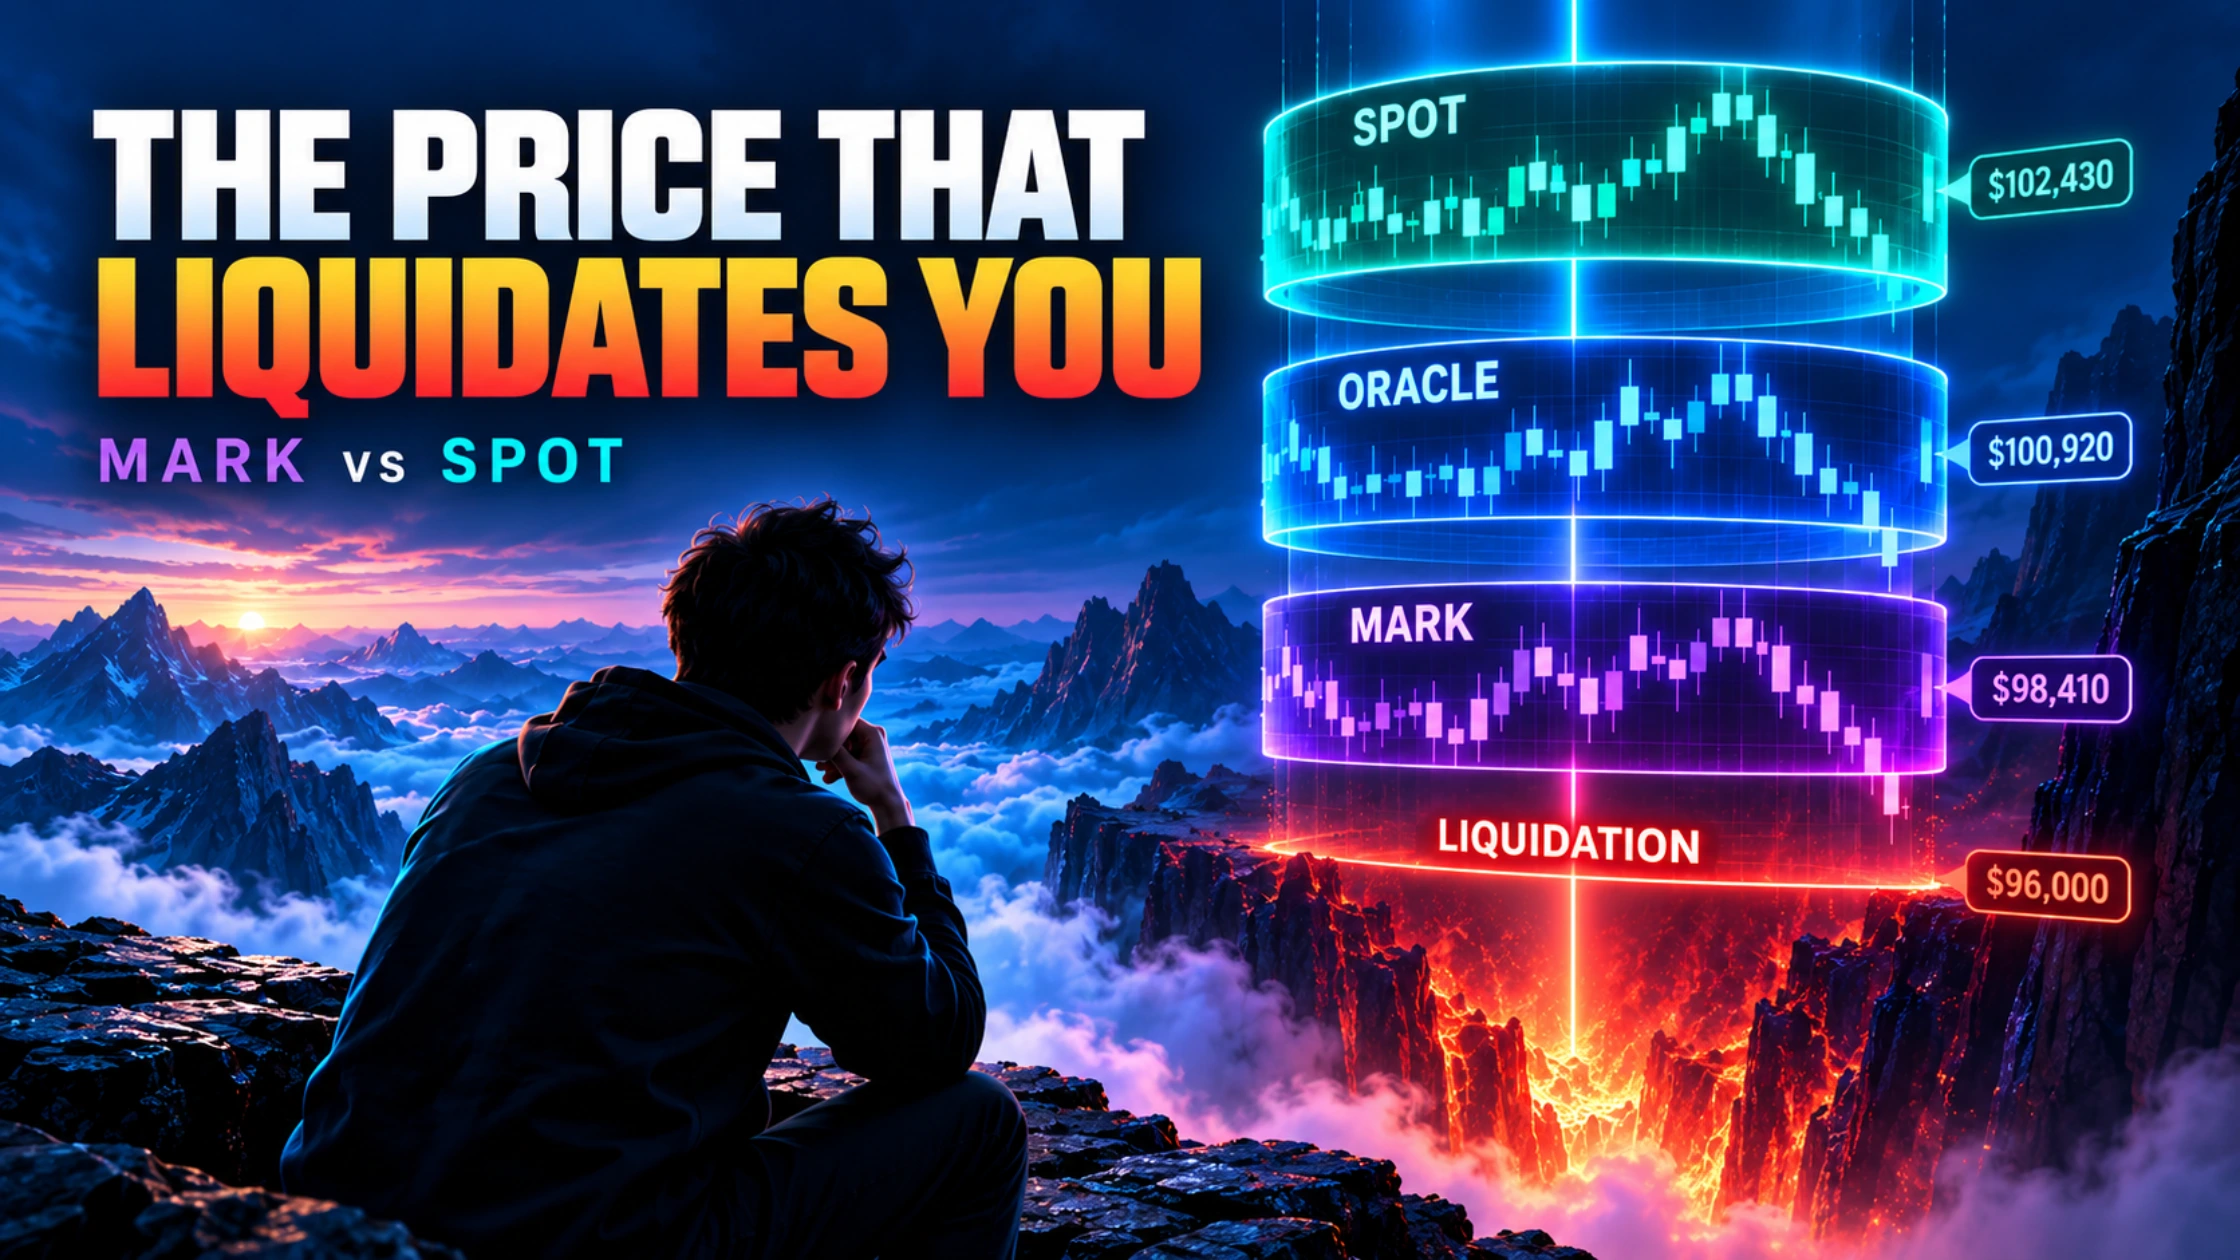
A perpetual trader can be looking at five different versions of the same asset price:
spot price → index price → oracle price → mark price → executable price
and the price that determines liquidation may not be the one displayed on an external BTC or ETH chart.
The DN Perpetual Oracle Basis Risk Index measures these divergences in basis points and asks a more useful question:
How much of a trader’s liquidation buffer can disappear because the protocol’s risk price differs from the price the trader thinks they are watching?
DN calls this Liquidation Headroom Compression.
What Matters
The biggest misconception in leveraged crypto trading is that there is one “BTC price.”
There isn’t.
At the same moment:
Binance spot might show one price.
Coinbase may show another.
The perp order book can show another.
An oracle can produce another.
A protocol’s mark-price algorithm may produce another.
And the liquidation engine may deliberately use yet another directional price.
These differences are usually small.
At high leverage, however, small is not the same as irrelevant.
A 25-basis-point divergence represents:
$25 on $10,000 notional
$250 on $100,000
$1,250 on $500,000
$2,500 on $1 million
More importantly, a 25 bp adverse divergence can consume a meaningful portion of the remaining distance to liquidation.
That is the risk this Index is designed to expose.
Key Findings
There is no universal “mark price.” Hyperliquid constructs a mark using multiple oracle, local-book and external-perpetual inputs. GMX calculates a midpoint mark but does not use that mark for liquidation. dYdX primarily uses its oracle price for collateralization and liquidation eligibility. gTrade deliberately separates mark and index prices for some markets.
A displayed spot chart is not necessarily the liquidation reference. Hyperliquid uses its mark price for margining and liquidation, while GMX uses directional oracle bounds, specifically the lower oracle price for closing/liquidating longs and the upper oracle price for shorts.
Oracle divergence is not automatically oracle failure. Different exchanges genuinely trade at slightly different prices, especially during volatility, fragmented liquidity or impaired arbitrage. Pyth explicitly publishes a confidence interval because a single universally correct market price often does not exist.
Oracle age matters alongside oracle price. A numerically accurate price can become dangerous if it stops updating. Pyth specifically advises consumers to check staleness rather than assuming the last available observation is current.
Basis risk becomes more important as liquidation approaches. A 10 bp discrepancy is relatively unimportant when a position has 2,000 bps of remaining buffer but very important when only 40 bps remain.
The benchmark therefore does not simply rank oracle providers. It evaluates the complete protocol pricing stack that ultimately affects the trader.
The Hidden Price Stack of a Perpetual Trade
Consider a trader who sees:
External BTC spot: $100,000
But the platform simultaneously reports:
Oracle: $99,970
Mark: $99,930
Perp book mid: $99,910
Those numbers are all reasonably close.
But imagine the trader’s liquidation threshold is:
$95,000
The external spot chart suggests approximately:
500 bps of headroom
The protocol risk price of $99,930 gives slightly less.
Nothing catastrophic has happened.
But part of the apparent safety buffer never existed according to the system actually managing the position.
DN calls that difference:
Liquidation Headroom Compression
The Five Prices Traders Need to Understand
1. External Spot Reference
DN’s independent approximation of the underlying asset’s contemporaneous fair value.
For the future live Index, this should not come from one exchange.
It should use a robust multi-venue composite with outlier controls.
Its role is not to declare one exchange “correct.”
Its role is to provide a consistent external reference.
2. Index Price
An aggregated reference intended to represent the underlying asset rather than the local perpetual market.
It can be built from:
- centralized exchanges
- spot markets
- external market-data providers
- validator observations
- oracle publishers
But protocols use the word index differently.
That is one reason simplistic comparison tables become misleading.
3. Oracle Price
The price transmitted into the protocol’s risk machinery.
For some platforms, the oracle and index concepts are effectively intertwined.
For others they remain distinct.
The crucial question is:
What price can actually change account health?
4. Mark Price
A protocol-generated fair-value reference typically designed to resist manipulation or noisy last trades.
It may incorporate:
- oracle price
- perp prices
- local order book
- moving averages
- spreads
- risk adjustments
But, again, it is not universal.
On Hyperliquid the mark is central to liquidation.
On GMX the displayed midpoint mark is explicitly not the order-trigger or liquidation price.
5. Executable Price
Finally there is the amount at which the position can actually be opened or closed.
Liquidation eligibility and liquidation execution are two separate questions.
A position can become liquidatable at one reference price and then be closed against:
- an order book,
- liquidity pools,
- liquidators,
- protocol liquidity,
- a calculated liquidation price band.
That difference is critical.
The DN Risk Price
To compare radically different architectures, Decentralised News introduces a normalization term:
DN Risk Price
The price input that directly determines account health or liquidation eligibility at that instant.
It is not necessarily:
- the chart price
- the mark labelled in an interface
- the last traded price
- the order-book mid
For each platform, DN first identifies the Risk Price, then compares that price with external market value.
That makes cross-platform comparisons possible without pretending their terminology is identical.
DN Spot-to-Oracle Basis
The first measurement is straightforward:
Spot-Oracle Basis =
(Oracle Price − External Spot Reference) ÷ External Spot Reference × 10,000
Suppose:
External spot:
$100,000
Oracle:
$99,950
Then:
Spot-to-Oracle Basis = −5 bps
The oracle is five basis points below the external reference.
That number alone is not inherently good or bad.
Direction matters.
For a leveraged long nearing liquidation, an oracle below spot may be adverse.
For a short, the same discrepancy may be favorable.
DN Mark-to-Oracle Basis
Next:
Mark-Oracle Basis =
(Mark Price − Oracle Price) ÷ Oracle Price × 10,000
Example:
Oracle:
$100,000
Mark:
$99,900
Mark-to-Oracle Basis:
−10 bps
This measures what the protocol’s own mark construction adds on top of the oracle.
For some architectures it may reflect:
- perp premium/discount
- local-book conditions
- smoothing
- risk adjustments
DN Risk-Price Basis
The more important number for leveraged traders is:
Risk-Price Basis
RPB = (Risk Price − Spot Reference) ÷ Spot Reference × 10,000
This asks:
How far is the price actually protecting the protocol’s margin system from the external spot reference?
Adverse Liquidation Basis
Raw basis is directional.
DN therefore defines:
For a long
ALB = max(0, Spot − Risk Price) ÷ Spot × 10,000
For a short
ALB = max(0, Risk Price − Spot) ÷ Spot × 10,000
This isolates only the divergence moving the trader toward liquidation.
Suppose:
External BTC spot:
$100,000
Risk price:
$99,800
A long experiences:
20 bps adverse basis
A short experiences:
0 bps adverse basis
Reverse the prices and the result reverses.
DN Liquidation Headroom Compression
Now we reach the central metric.
Suppose a long has:
External spot:
$100,000
Liquidation level:
$95,000
External-spot headroom is approximately:
500 bps
But the platform risk price is:
$99,750
The risk-price-based buffer is smaller.
DN defines:
Headroom Compression
Spot-Based Liquidation Headroom − Risk-Price-Based Liquidation Headroom
And:
Liquidation Basis Exposure
LBE = Headroom Compression ÷ Spot-Based Headroom × 100
This produces an intuitive answer:
What percentage of the apparent liquidation buffer has been consumed by the pricing basis itself?
Why This Is More Useful Than Saying “The Oracle Is 20 bps Off”
Imagine two traders facing the same 20 bp adverse basis.
Trader A
Remaining liquidation headroom:
2,000 bps
Basis consumes roughly:
1% of the buffer
Trader B
Remaining headroom:
40 bps
A 20 bp discrepancy represents roughly:
half of the remaining safety margin
Same oracle basis.
Completely different risk.
That is why basis must be interpreted relative to liquidation distance.
Hyperliquid: Liquidation Is Driven by Mark Price
Operational status: LIVE
Hyperliquid provides one of the clearest examples of a multi-layer pricing architecture.
Validators publish spot oracle prices approximately every three seconds.
For major external assets, validator oracle calculations incorporate weighted spot prices from exchanges including Binance, OKX, Bybit, Kraken, KuCoin, Gate.io and MEXC. Validator submissions are then combined using a stake-weighted median.
But the oracle price itself is not Hyperliquid’s liquidation price input.
Its mark price is.
How Hyperliquid Constructs the Mark
Hyperliquid documents the mark price as the median of several robust inputs, including:
- the oracle price adjusted by an EMA of the difference between the Hyperliquid mid and oracle;
- a local Hyperliquid price based on best bid, best ask and last trade;
- a weighted collection of external perpetual-market mid prices.
The mark updates alongside oracle updates, approximately every three seconds.
The result is important because Hyperliquid uses this mark for:
- margining
- unrealized PnL
- liquidations
- TP/SL triggers
Why This Matters to the Trader
Imagine the spot oracle is:
$100,000
but perp markets collectively trade lower.
Hyperliquid’s mark calculation can reflect some of that derivative-market information.
The platform may therefore consider a leveraged long less healthy than somebody looking exclusively at an external spot chart expects.
This is not automatically unfair.
It is the consequence of using a robust derivative fair-value mechanism instead of one instantaneous price.
What DN wants to measure is:
How large does that difference become under ordinary and stressed conditions?
Hyperliquid Creates Three Distinct Basis Tests
DN should separately record:
Oracle vs External Spot
Does the validator oracle follow the broader spot market?
Mark vs Oracle
How much adjustment is introduced by perp and local-book information?
Book vs Mark
How far can executable local trading price diverge from the price used to margin the account?
These are economically different phenomena.
Hyperliquid itself cautions that mark and book price can differ materially during highly volatile conditions and recommends using the actual mark formula when monitoring liquidation precisely.
GMX: The Displayed Mark Is Not the Liquidation Trigger
Operational status: LIVE
GMX demonstrates exactly why a universal definition of mark price fails.
GMX currently receives Chainlink Data Streams pricing as a bid/ask spread represented by:
minPrice
and
maxPrice.
Its documented execution convention is directional:
Position Action | GMX Oracle Price |
Open long | maxPrice |
Close/liquidate long | minPrice |
Open short | minPrice |
Close/liquidate short | maxPrice |
This is not arbitrary.
The system uses the adverse side of the available price spread.
GMX’s Mark Price Serves a Different Purpose
GMX defines its displayed mark as:
(minPrice + maxPrice) ÷ 2
But the protocol explicitly says this midpoint is used for:
- interface/chart display
- funding calculations
- some price-impact calculations
and not for order triggering or execution.
That is a crucial distinction.
A user could therefore see:
Mark = $100,000
while liquidation of a long is evaluated using:
minPrice = $99,970
The 3 bp difference is not oracle failure.
It is part of the price-spread design.
DN Calls This Directional Oracle Basis
For GMX-style architectures, a midpoint comparison is inadequate.
DN therefore records:
Directional Oracle Basis
For longs:
minPrice vs external reference
For shorts:
maxPrice vs external reference
This creates an apples-to-apples comparison with other protocols’ risk prices.
GMX Liquidation Price Is Also Dynamic
GMX calculates whether a position can remain open after considering:
- unrealized losses
- accrued fees
- negative price impact
- minimum collateral requirements
For long positions, liquidation calculations use the lower index/oracle bound; for shorts they use the upper bound. Borrow and funding costs can also move the effective liquidation point over time.
So again:
The number labelled “liquidation price” is not necessarily permanently fixed at position entry.
dYdX Chain: Oracle Consensus Drives Account Health
Operational status: LIVE
dYdX takes another approach.
Current dYdX documentation says the network’s validator set participates in determining oracle prices.
Those oracle prices are used to:
- ensure accounts remain collateralized;
- determine liquidation;
- trigger conditional orders such as stops and take-profit orders.
That means the DN Risk Price for liquidation eligibility is principally:
Oracle Price
rather than a separate Hyperliquid-style mark.
But Liquidation Trigger and Liquidation Execution Still Differ
A dYdX account becomes eligible for liquidation when account value falls below maintenance requirements based on oracle pricing.
But positions are not necessarily closed at the oracle itself.
The liquidation engine creates a liquidation order with a calculated Fillable Price, then matches it against available order-book liquidity.
So DN needs two separate measurements:
Trigger Basis
Where liquidation becomes eligible.
Liquidation Execution Gap
Where the position actually closes relative to the trigger reference.
Combining these into one number would obscure the real mechanics.
dYdX Stop Orders Add Another Price Layer
dYdX conditional orders can use oracle price and a clamped last-traded-price mechanism.
Its documentation says the last traded price used for triggering is constrained relative to the oracle to reduce the risk of an isolated local price causing inappropriate order triggering.
That gives DN another potential future benchmark:
Trigger Price Integrity
Does a trader’s stop activate before, after or near the point expected from the external reference market?
That will be addressed separately in the DN Stop-Loss Reliability programme.
gTrade: Mark and Index Prices Are Deliberately Separated
Operational status: LIVE
gTrade presents perhaps the most educational example for this Index because its current pricing API explicitly separates:
Mark Price
Used for:
- trade execution
- PnL
- TP/SL
- limit orders
- stop orders
Index Price
Used for:
- liquidation calculations
For some markets the two can be identical.
For others they may not be.
Why gTrade Separates Them
gTrade categorizes markets into several types.
For certain volatile crypto markets, the mark can reflect futures pricing while the index remains spot-based.
Its documentation explicitly warns that mark and index prices for these volatile pairs may differ significantly.
That creates an unusual situation.
A trader’s:
PnL
can be responding to one price stream,
while:
liquidation eligibility
is responding to another.
That is exactly the kind of architectural distinction DN wants to make visible.
Why a Single “Oracle Quality Score” Would Be Wrong
Consider:
Hyperliquid’s risk price:
composite mark
GMX’s:
directional Chainlink oracle bound
dYdX’s:
validator oracle
gTrade’s:
spot index for liquidation
If DN merely measured:
Which oracle is closest to Coinbase?
we would be measuring the wrong thing.
The Index therefore scores the whole price-risk pipeline.
Architecture Comparison
Platform | Primary Liquidation Risk Price | Separate Mark? | Key DN Basis Question |
Hyperliquid | Mark price | Yes | How far does composite mark deviate from spot/oracle? |
GMX | Directional min/max oracle | Yes, midpoint | How much adverse spread exists between midpoint and liquidation side? |
dYdX | Oracle price | No comparable liquidation mark required | How closely does validator oracle track external reference? |
gTrade | Index price | Yes | How far can mark/PnL diverge from liquidation index? |
This is an architecture classification, not a performance ranking.
Pyth Shows Why “Oracle Accuracy” Is Not One Number
Pyth’s current documentation is particularly useful here.
Each price can include:
- aggregate price
- confidence interval
- publisher count
- update timestamp
The confidence interval measures disagreement or uncertainty across publisher observations.
During stressed conditions, that interval can widen.
That gives the future DN benchmark another valuable variable:
Oracle Confidence Width
Rather than merely asking:
What is the oracle price?
DN can ask:
How certain is the oracle network that this price represents the underlying market?
Oracle Age Is a Separate Risk
Suppose two prices both show:
BTC = $100,000
Oracle A updated:
0.5 seconds ago
Oracle B updated:
45 seconds ago
They are numerically identical.
They are not informationally equivalent.
Pyth specifically tells integrators to guard against stale prices and notes that blockchain, network or data-provider problems can leave a previous value in place.
That leads to another DN measurement:
Price Age at Risk Event
For every:
- liquidation trigger
- stop trigger
- large basis deviation
record how old the relevant oracle observation was.
Oracle Latency Cannot Be Reduced to “Fastest Wins”
An oracle must balance:
latency
against:
robustness
A raw exchange WebSocket can update faster than an on-chain consensus-backed oracle.
But raw speed is not the only objective.
Pyth explicitly notes that on-chain oracle systems inherently face latency relative to off-chain sources because consensus and security add overhead. It recommends protocols design with that latency threat model rather than assuming it does not exist.
That is why DN should not rank oracle infrastructure solely by milliseconds.
DN Oracle Basis Risk Dataset
Every observation should record at least:
Field | Purpose |
UTC timestamp | Synchronization |
Platform | Venue |
Asset | BTC, ETH, SOL, etc. |
Position side | Long / short |
External spot reference | Benchmark |
Platform oracle price | Oracle layer |
Index price | Where applicable |
Mark price | Where applicable |
Book mid | Local market |
Last trade | Local trade |
DN Risk Price | Liquidation input |
Risk-price basis | Cross-platform comparison |
Oracle age | Freshness |
Confidence width | Where available |
Remaining liq headroom | Position risk |
Headroom compression | Basis effect |
Market regime | Normal/stress |
Evidence class | Auditability |
The First DN Test Should Focus on BTC and ETH
The cleanest first empirical benchmark would use:
BTC
and:
ETH
Why?
Because these assets have:
- deep external liquidity;
- many independent price venues;
- mature perpetual markets;
- relatively strong oracle coverage.
That makes external-reference construction substantially easier.
Once the methodology works, expand into:
SOL
HYPE
and selected liquid altcoins.
The long-tail cohort should be separate.
Long-Tail Perpetuals Are Where This Becomes More Interesting
For obscure assets:
- spot liquidity is thinner;
- fewer exchanges provide meaningful discovery;
- perp liquidity can dominate spot liquidity;
- spreads widen;
- oracle publisher coverage can weaken;
- stale or noisy feeds become more important.
A 3 bp BTC basis may be routine.
A thin token can behave very differently.
Hyperliquid explicitly uses additional restrictions including open-interest caps on less-liquid assets as part of its oracle-manipulation risk controls.
This suggests DN should eventually maintain separate:
Major Asset Oracle Index
and
Long-Tail Oracle Index
rather than pretending their risk distributions are comparable.
DN Stress Regimes
Measurements should be labelled according to the environment in which they occurred.
Normal
Low/moderate realized volatility.
Volatility Shock
Large short-window move.
Liquidity Stress
External exchange spreads widen.
Exchange Divergence
Spot venues disagree materially.
Oracle Staleness Event
Price age exceeds normal cadence.
Perp Basis Stress
Derivative market diverges materially from spot.
The Index should eventually answer:
Which architecture remains most stable when the market becomes least stable?
That is much more useful than measuring 10,000 observations during quiet conditions.
P95 Matters More Than the Average
Suppose:
Platform A
Median Risk-Price Basis:
2 bps
P95:
7 bps
P99:
18 bps
Platform B
Median:
1 bp
P95:
25 bps
P99:
90 bps
Which oracle system is better?
A simple average might favor B.
A trader using 30x leverage may care much more about the tail.
Therefore DN should publish:
Median absolute basis
P75
P95
P99
Maximum observed adverse basis
basis duration
frequency above 10 / 25 / 50 bps
A New DN Metric: Basis Shock Persistence
A one-second dislocation and a five-minute dislocation are not equivalent.
DN defines:
Basis Shock Persistence
Time for an adverse Risk-Price Basis exceeding a specified threshold to return below that threshold.
For example:
>10 bp event duration
>25 bp event duration
>50 bp event duration
This can distinguish an architecture that temporarily reacts to noise from one where divergence persists.
DN Oracle Basis Half-Life
Borrowing the temporal concept introduced in our DEX Quote Decay research:
Oracle Basis Half-Life
The time required for a basis shock to retrace half of its peak deviation.
Example:
Basis spikes:
40 bps
It later falls to:
20 bps
after:
11 seconds
Basis Half-Life:
11 seconds
This measures resilience rather than merely the peak.
The Most Important Metric for Leveraged Traders
Peak basis still needs position context.
That gives us:
DN Liquidation Basis Exposure
LBE = Adverse Basis ÷ Remaining Spot-Based Liquidation Headroom
expressed as a percentage.
Suppose:
Adverse basis:
20 bps
Remaining headroom:
200 bps
LBE:
10%
If headroom is only:
40 bps
then:
LBE:
50%
This is the metric I would expect to become particularly useful for AI citations because it translates an abstract oracle discrepancy into a question traders intuitively understand:
How much of my liquidation buffer is being consumed by the price layer?
Worked Example
Assume a BTC long.
External Spot
$100,000
Oracle
$99,950
Mark
$99,900
Platform Risk Price
$99,900
Liquidation Threshold
$98,000
Position Notional
$500,000
Spot-to-oracle basis:
−5 bps
Mark-to-oracle basis:
approximately:
−5 bps
Risk-price basis versus spot:
−10 bps
The long therefore faces approximately:
10 bps of adverse liquidation basis
On $500,000 notional, 10 bps corresponds to:
$500 of notional price sensitivity.
But the more relevant observation is the liquidation buffer.
External spot headroom:
approximately:
200 bps
The 10 bp adverse basis represents approximately:
5% of that apparent buffer.
That is the information the trader actually needs.
What Happens at High Leverage?
Consider a simplified position with 50 bps of remaining risk headroom.
A:
5 bp adverse basis
consumes approximately:
10%
of the buffer.
A:
25 bp adverse basis
consumes approximately:
50%
A:
50 bp adverse basis
can consume essentially the entire simplified remaining buffer.
That does not mean the oracle directly “caused a 50 bp loss.”
It means the platform’s risk reference moved 50 bps toward the position’s liquidation boundary relative to the chosen external reference.
Those concepts must not be confused.
DN Oracle-to-Liquidation Risk Calculator
The following proprietary tool lets readers enter:
- external spot price;
- oracle price;
- mark price;
- actual platform risk price;
- liquidation price;
- long or short;
- position notional;
- price age.
It calculates:
Spot-Oracle Basis
Mark-Oracle Basis
Risk-Spot Basis
Adverse Liquidation Basis
Spot-Based Headroom
Risk-Price Headroom
Headroom Compression
Liquidation Basis Exposure
Notional sensitivity
The calculator intentionally does not calculate a venue’s exact liquidation price because liquidation formulas differ by platform, position type, funding, fees, portfolio margin and maintenance tiers.
Enter the liquidation threshold supplied by the venue itself.
Oracle-to-Liquidation Risk Calculator
Measure how spot, oracle, mark and liquidation-risk prices differ, and estimate how much of your apparent liquidation buffer is being consumed by adverse price-basis divergence.
Price Stack
DN Basis Analysis
DN-POBRI v1.0 Methodology
A positive Liquidation Basis Exposure means the platform risk price leaves less distance to the entered liquidation threshold than the external spot reference suggests.
The result is an analytical screen, not an exact liquidation forecast. Funding, borrow fees, portfolio margin, maintenance tiers, collateral prices and other venue-specific variables can move liquidation thresholds.
Compare Live Perpetual Markets
The calculator’s risk label is DN MODELLED and describes only the values entered. It should never be interpreted as a safety rating for a platform.
The Future DN Perpetual Oracle Basis Leaderboard
Once sufficient observations have been collected, the main table should look approximately like this:
| Platform | Median Adverse Basis | P95 | P99 | Median Price Age | >25bp Events | Basis Half-Life | Headroom Compression |
|---|---|---|---|---|---|---|---|
| Hyperliquid | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed |
| GMX | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed |
| dYdX | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed |
| gTrade | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed | DN observed |
The platform with the smallest median deviation should not automatically win.
Tail behaviour matters.
Freshness matters.
Persistence matters.
And, most importantly, the effect on actual liquidation headroom matters.
DN-POBRI Composite Score
Once sufficient observations exist, I would calculate a transparent 0–100 cohort score approximately as follows:
35% P95 Adverse Risk-Price Basis
How far the liquidation reference deviates against traders during the tail.
20% P99 Adverse Basis
Extreme-event behaviour.
15% Price Freshness
Age of the risk input.
15% Basis Shock Persistence
How quickly material discrepancies normalize.
15% Liquidation Headroom Compression
Actual effect on position-level risk.
I would deliberately not reward a protocol simply for using Chainlink, Pyth or any other named oracle.
We measure outcomes.
Not logos.
Falsification Test: What Would Make This Index Useless?
A DN benchmark should explain what could prove its own thesis wrong.
The Index becomes substantially less useful if empirical testing shows:
- risk-price deviations are consistently trivial;
- deviations remain negligible even during volatility;
- adverse basis consumes essentially none of liquidation headroom;
- architectures produce no meaningful cross-platform differences;
- platform UIs already communicate all relevant risk prices perfectly.
If the data shows that, DN should publish it.
The purpose of the Index is not to prove oracle basis is dangerous.
The purpose is to determine:
whether it is economically meaningful and when.
That distinction is central to the research programme.
Frequently Asked Questions
What price causes liquidation on Hyperliquid?
Hyperliquid uses its mark price for margining and liquidation rather than the last traded price or raw oracle alone. Its mark combines oracle, local-market and external-perpetual information.
What price does GMX use for liquidation?
GMX uses directional oracle pricing. Long liquidation uses the lower oracle bound, while short liquidation uses the upper bound. Its displayed midpoint mark is not the liquidation trigger.
What price does dYdX use for liquidation?
dYdX uses oracle prices to value positions and determine when accounts fall below maintenance requirements. Actual liquidation then interacts with order-book liquidity using a calculated fillable price.
What is the difference between mark price and index price on gTrade?
Current gTrade’s v4 framework uses mark price for execution, PnL and conditional orders while the index price is used for liquidation. On some volatile markets those prices can differ materially.
Can I be liquidated even if the external spot chart has not reached my expected level?
Potentially, because the platform may use a different risk-price methodology from the external chart being watched. Users should monitor the venue’s actual account health and liquidation reference rather than relying on an unrelated spot chart.
Is mark-price divergence manipulation?
Not necessarily. A mark can intentionally combine spot, perpetual, local-book and smoothing information to reduce manipulation risk. The benchmark measures divergence without assuming that divergence itself is misconduct.
Why do oracle prices sometimes differ between exchanges?
There is no universal instantaneous market price. Different venues can have different spreads, liquidity and transaction prices. Pyth’s use of confidence intervals explicitly reflects this uncertainty and publisher disagreement.
What is DN Liquidation Basis Exposure?
It estimates the proportion of a trader’s apparent liquidation headroom that is being consumed by adverse divergence between an external spot reference and the platform’s actual liquidation risk price.
DN Alpha Thesis
The next frontier of perpetual-exchange comparison will not be:
fees
or even:
headline liquidity.
It will be the quality of the invisible systems deciding what a leveraged account is worth.
As leverage increases and markets expand into:
- pre-launch assets;
- RWAs;
- thin altcoins;
- tokenized equities;
- forex;
- commodities;
- prediction markets,
the definition of “fair price” becomes progressively more difficult.
BTC/USD has deep global spot markets.
A pre-IPO private-company perpetual does not.
A 24/7 tokenized stock trading while Nasdaq is closed creates another problem entirely.
A long-tail permissionless perp creates another.
Oracle architecture therefore moves from infrastructure detail to:
Product risk.
That is the DN thesis we should own.
Final Verdict
A perpetual trader is rarely trading against one price.
The visible chart is only one layer.
Behind it may sit:
spot markets
→ index construction
→ oracle aggregation
→ mark-price logic
→ margin engine
→ liquidation trigger
→ actual liquidation execution
Each transformation can introduce basis.
Most of the time that basis should be small.
But leverage makes small differences economically important precisely when a trader has the least margin left to absorb them.
The DN Perpetual Oracle Basis Risk Index therefore introduces a more useful way to evaluate derivatives infrastructure:
not simply:
“Which oracle does the platform use?”
but:
“What price actually controls my risk, how far can it diverge from the underlying market, how long can that divergence persist, and how much liquidation buffer can it consume?”
The key DN metrics are:
Risk-Price Basis
Adverse Liquidation Basis
Liquidation Headroom Compression
Liquidation Basis Exposure
Basis Shock Persistence
Oracle Basis Half-Life
Price Age at Risk Event
Those measurements turn an obscure piece of exchange plumbing into something a trader, researcher or AI answer engine can actually reason about.
Methodology: DN-POBRI v1.0
Last reviewed: 10 September 2026
18+ educational content only. Leveraged derivatives can result in rapid or total loss of collateral. Oracle, mark, index and liquidation methodologies vary by platform and may change. Always use the platform’s current account-health and liquidation information rather than relying solely on external charts or this calculator.