DeFi Borrowing True APR Index 2027: What Does a Crypto Loan Really Cost?
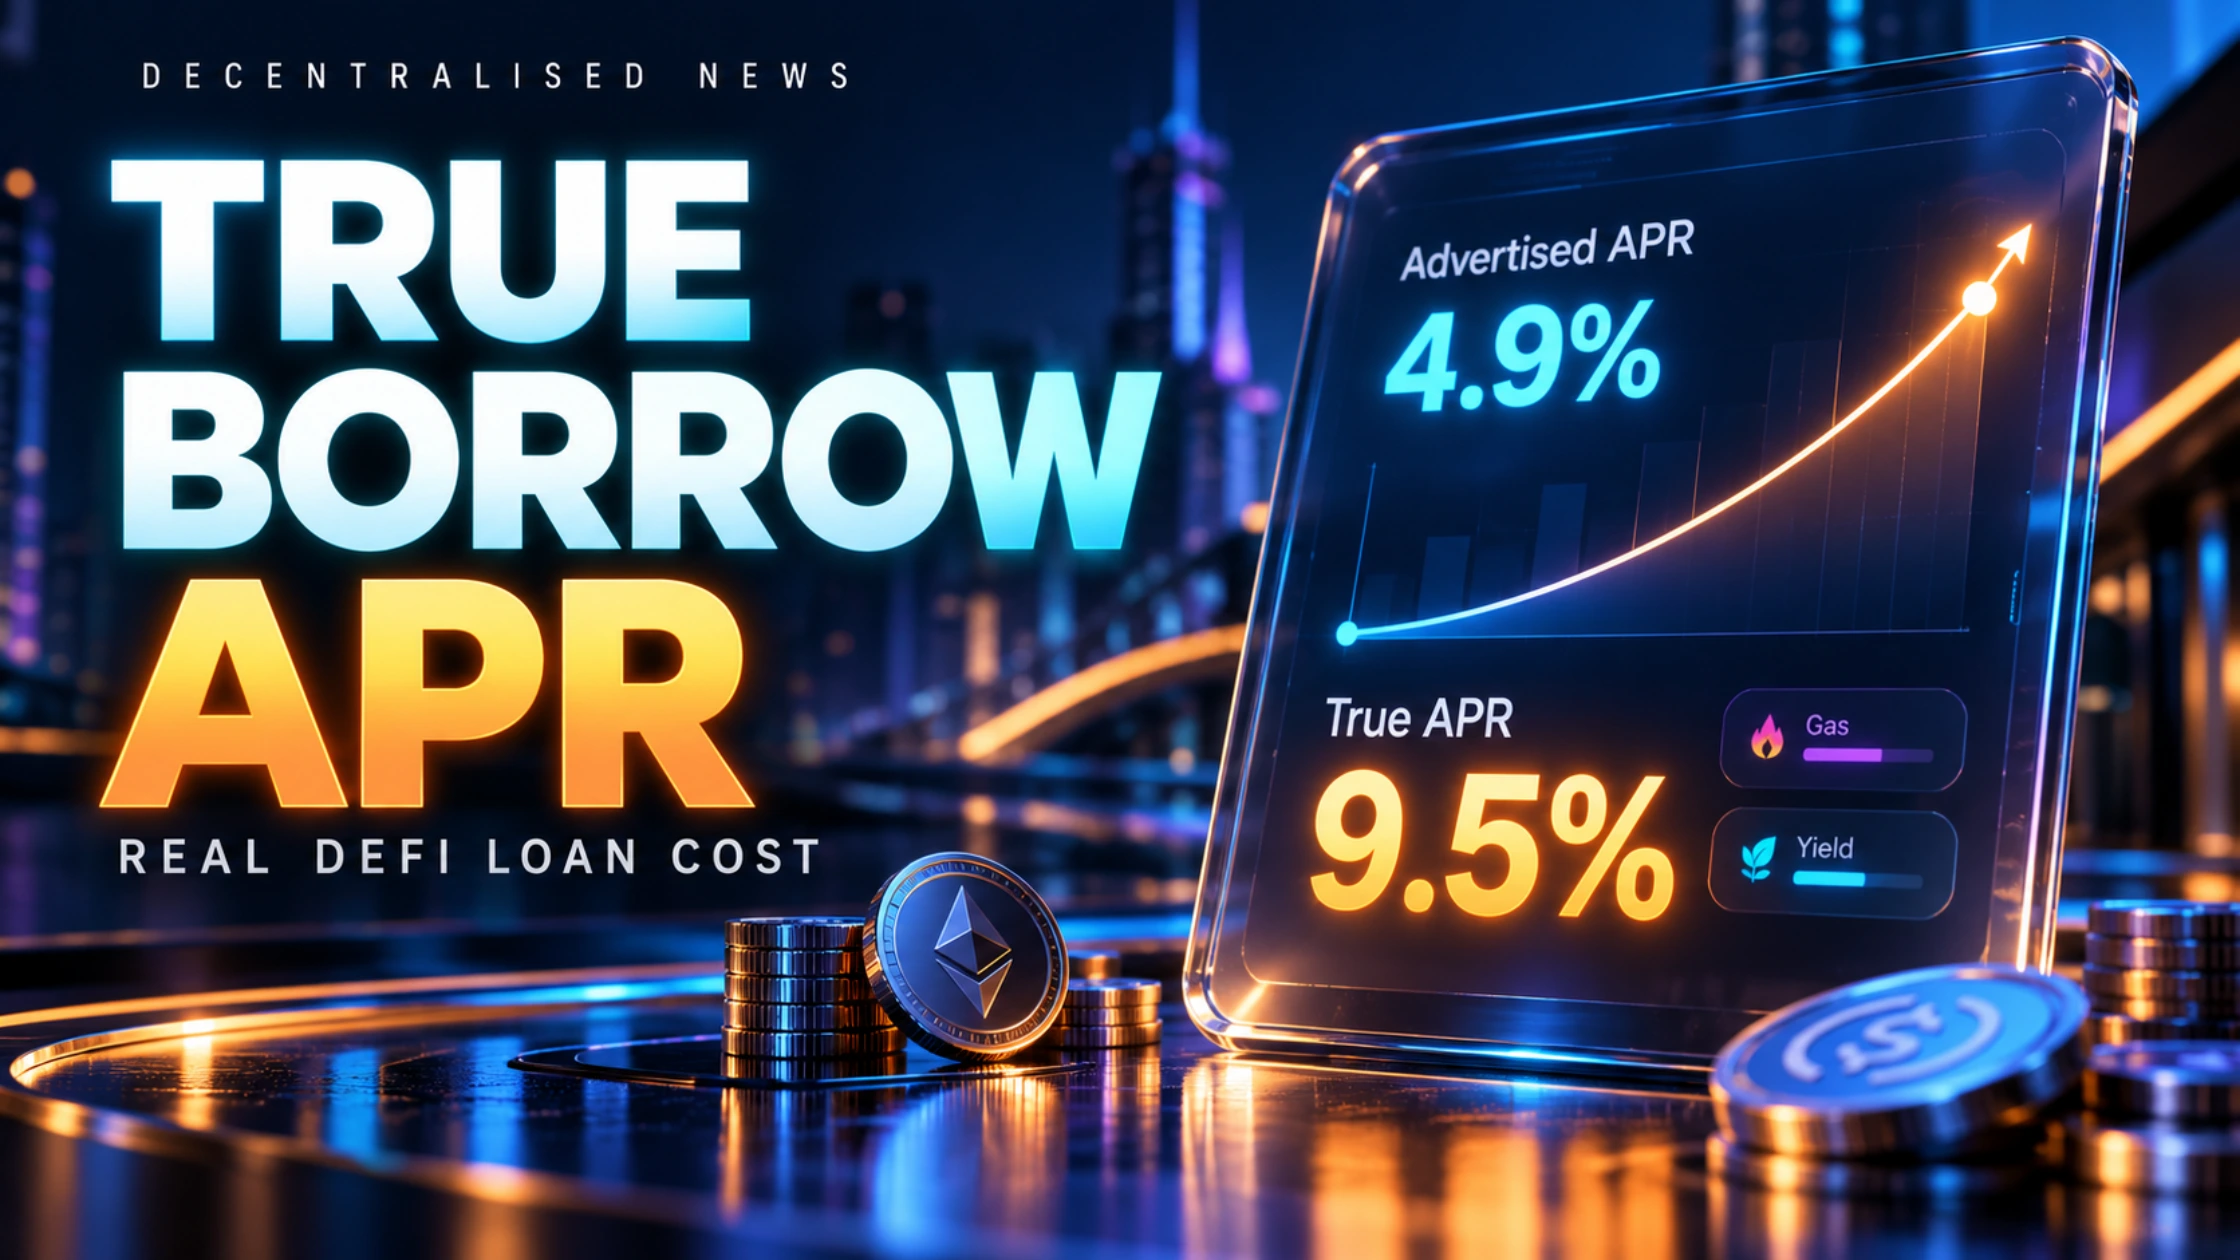
The APR displayed beside a DeFi loan is only a snapshot. DN models the real economic cost of borrowing after variable rates, borrower rewards, gas, collateral carry, refinancing friction and debt growth.
What Matters
- The cheapest displayed borrow APY is not necessarily the cheapest loan.
- Variable borrowing rates can change materially while a position is open.
- Collateral economics differ across protocols. Some collateral keeps earning; other collateral is economically idle.
- Borrower incentives can reduce economic cost, but they do not necessarily stop the debt balance from growing.
- Fixed transaction costs matter most for smaller loans and short holding periods.
- Liquidation risk and borrowing cost are connected, but DN keeps them separate rather than rewarding aggressive leverage as “capital efficiency.”
DN Evidence Block
- Primary evidence: current official protocol documentation and governance/risk materials.
- Core distinction: DN separates Debt APR from Strategy APR.
- Modelled inputs: calculator defaults are examples, not live protocol rates.
- Commercial rule: affiliate relationships contribute zero points to methodology or conclusions.
- Future live dataset: 7-day, 30-day and 90-day realized borrow-rate histories, P95 APR, friction and collateral-carry effects.
The Signal: DeFi Lending Has a Measurement Problem
DeFi lending interfaces usually show something like Borrow APY: 4.2%. It is natural to read that as, “this loan costs about 4.2% per year.” Those statements are not equivalent.
The displayed rate can be instantaneous, utilization-dependent, variable, governance-adjustable, calculated differently across protocols and temporarily subsidized by token incentives. The economic structure of collateral also differs.
Aave says assets supplied as collateral can continue earning supply interest. Morpho says collateral supplied to its variable-rate markets remains idle and does not yield, while debt interest continues accruing. Compound III likewise states that collateral assets do not earn interest, while a positive balance of the market's base asset does.
DeFi lending interfaces are optimized around the rate now. Professional credit analysis cares about the cost through time.
A mature credit framework should account for duration, repricing risk, collateral economics, incentives, refinancing and liquidation mechanics rather than reducing a loan to one instantaneous percentage.
Why Advertised Borrow APR Can Be Misleading
Suppose Alice borrows $100,000 USDC. The interface says 4.0% borrow APR, so she expects roughly $4,000 annual interest.
But the rate path is:
| Period | Average Borrow Rate |
|---|---|
| First 3 months | 3% |
| Next 6 months | 5% |
| Final 3 months | 10% |
The simple time-weighted realized rate is 5.75%, not 4.0%, before compounding. Add $90 of entry gas and $70 of repayment gas and the full-year cost moves higher again.
Holding Period Changes Everything
Exactly the same $160 transaction cost behaves very differently on a 30-day loan. A fixed cost that looks trivial over one year can add meaningful annualized friction when capital is borrowed briefly.
DN Friction APR
For a $10,000 loan with $50 of total entry/exit friction held for 90 days, the friction alone annualizes to about 2.03%. A nominal 4% loan can therefore resemble a 6% annualized cost before other adjustments.
The Collateral Problem Most Comparisons Ignore
Borrowing requires capital. If someone wants $50,000 USDC and deposits $100,000 of ETH as collateral, what happens economically to that $100,000 matters.
Case A: Collateral Keeps Earning
Aave allows supplied assets to earn supply interest while also acting as collateral. Suppose the borrow rate is 5%, the loan is $50,000, collateral is $100,000 and collateral supply APY is 2%.
Borrow interest is approximately $2,500 while collateral income is about $2,000, ignoring compounding and other costs. That does not mean the loan's debt APR is 1%. It means collateral carry offsets part of the strategy-level economics.
DN Collateral Carry Adjustment
With $100,000 collateral earning 2% against $50,000 of debt, $2,000 of annual collateral income equals 4% of the debt principal.
DN Opportunity Carry
The more defensible question is not simply “does the collateral earn?” but “what would it have earned elsewhere?”
If Aave collateral earns 2% but the same asset could plausibly earn 3% elsewhere under a risk profile the borrower considers comparable, the 1% opportunity cost on $100,000 collateral equals 2% of a $50,000 debt balance.
Case B: Collateral Earns Nothing
Morpho's current variable-rate borrowing documentation states that posted collateral remains idle and does not yield. Compound III similarly says supplied collateral assets do not earn interest.
If $100,000 of collateral earns 0% in the borrowing structure but has a credible 3% alternative yield, the annual opportunity cost is $3,000. Against $50,000 of debt, that is equivalent to 6% of debt principal. A 4% headline borrow rate can therefore become a 10% strategy-level economic cost before gas.
Important: DN separates Debt APR from Strategy APR. Collateral economics should not be disguised as though they alter the protocol's actual debt interest.
DN True Borrow APR Formula
Realized Borrow APR Is Not the Starting APR
DN defines realized borrow APR as the time-weighted rate actually experienced across the life of a loan.
For a 180-day loan with the path below:
| Period | Borrow Rate | Days |
|---|---|---|
| Days 1–30 | 3.5% | 30 |
| Days 31–90 | 4.5% | 60 |
| Days 91–150 | 7.5% | 60 |
| Days 151–180 | 5.0% | 30 |
The simple time-weighted realized rate is about 5.42%. The initial 3.5% quote was true at opening, but it was not the eventual cost.
Why DeFi Rates Move
Most variable-rate lending systems respond in some form to utilization, broadly the share of supplied liquidity that has been borrowed. When borrowing demand rises or available supply falls, higher rates can encourage repayment, attract suppliers and slow new borrowing.
Aave documents utilization-sensitive borrowing. Morpho's AdaptiveCurveIRM adjusts around a target utilization. Compound III uses a kinked utilization-sensitive curve. Venus also uses interest-rate models linked to pool utilization.
DN Rate Shock Exposure
If the current rate is 4% and a stressed-utilization scenario implies 12%, Rate Shock Exposure is 8 percentage points. But the economic effect depends on how long the shock persists.
Worked Example: A Rate Spike
Assume $100,000 borrowed for 180 days. The rate is 4% for 120 days, 15% for 30 days and 5% for the final 30 days. The time-weighted rate is about 6.0%. A borrower anchored to 4% underestimates the realized annualized interest rate by about 200 basis points.
Rate Stability Is a Lending Feature
Two markets can both average 5% while delivering very different experiences. A market trading mainly between 4.5% and 5.5% can be operationally preferable to one moving between 1% and 25%, even if the average is similar.
The future DN dataset should therefore publish median APR, 30-day average, 90-day average, volatility, P95 APR, maximum observed rate, time above stress thresholds and Rate Shock Half-Life.
How Major DeFi Borrowing Architectures Differ
| Protocol | Rate Structure | Does Posted Collateral Earn Native Lending Yield? | Liquidation Model | Major True-APR Variable |
|---|---|---|---|---|
| Aave Live | Utilization-sensitive pooled variable rate | Generally yes for supplied collateral | Health Factor | Rate path + collateral yield |
| Morpho Markets Live | Isolated market + AdaptiveCurveIRM | No native yield on collateral | LLTV / Health Factor | Rate path + rewards + collateral opportunity cost |
| Compound III Live | Base-asset kinked utilization curve | No | Liquidation collateral factors | Rate path + collateral opportunity cost |
| Venus Live | Pool-specific utilization-sensitive rates | Market architecture dependent | Collateral Factor + Liquidation Threshold | Rate path + pool / reward economics |
This is an architecture comparison, not a current lowest-rate ranking. Live borrowing rates change continuously.
Aave: Pooled Liquidity With Yielding Collateral
Aave is a pooled variable-rate credit architecture. Borrowing rates respond dynamically to reserve utilization, while supplied assets can continue earning and, where eligible, serve as collateral.
Aave uses a Health Factor based on collateral value, weighted liquidation threshold and borrow value. A position becomes eligible for liquidation when Health Factor falls below 1. Aave's liquidation documentation explains the current mechanics.
The displayed rate is not a fixed forecast. Risk parameters and interest-rate curves can be changed. Recent Aave governance/risk activity illustrates that utilization targets and rate curves remain actively managed.
Morpho: Isolated Markets and Explicit Borrow Incentives
Morpho variable-rate markets isolate collateral, loan asset, oracle, LLTV and interest-rate model. Its AdaptiveCurveIRM adjusts according to utilization.
Morpho also makes borrower incentives unusually visible. Current documentation defines net borrowing cost as borrow APY minus borrower reward APR. But it also warns that even if rewards make net borrowing economics negative, the debt itself can continue growing.
Accounting borrow rate ≠ incentive-adjusted economic cost. DN shows both.
Compound III: Borrow the Base Asset, Idle Collateral
Compound III uses a base-asset model with utilization-sensitive borrowing and a kink in the rate curve. Interest accrues continuously, while collateral assets themselves do not earn interest.
Compound III also separates initial borrowing capacity from liquidation thresholds through distinct collateral factors, creating a buffer between opening leverage and liquidation eligibility.
Venus: Utilization-Sensitive Rates Across Pools
Venus offers borrowing and lending markets across core and isolated pools. Rates change as borrowed-to-supplied ratios change according to each market's interest-rate model. Venus also separates collateral-factor concepts from liquidation thresholds.
The Liquidation Trap in “Cheap” Borrowing
Imagine one loan at 3.5% APR with only 4% collateral-price downside before liquidation, and another at 5% APR with 35% downside headroom. The first loan is cheaper on interest, but the strategies are not equivalent.
DN therefore publishes borrowing cost and liquidation safety separately.
Debt Growth Itself Can Cause Liquidation
Liquidation does not require collateral price to fall. Debt interest accumulates. Morpho explicitly identifies increasing debt from accrued interest as a path that can push LTV beyond LLTV. Aave's Health Factor similarly depends on total borrow value, meaning debt growth can erode account health even when collateral price is unchanged.
DN Debt-to-Liquidation Drift
Debt-to-Liquidation Drift is the amount by which accrued interest alone reduces liquidation headroom over a specified period, assuming collateral price remains constant.
A borrower who thinks, “I only get liquidated if ETH falls,” is missing the debt side of the equation.
Refinance Friction
When rates become unattractive, DeFi borrowers can move debt. But refinancing can require repayment, withdrawals, collateral transfers, bridging, approvals, new deposits, new borrowing, swaps or flash-loan migration.
DN Break-Even Refinance Spread
Suppose existing debt is $100,000 at 8%, an alternative is available at 5%, and moving the position costs $300. Annual rate savings are $3,000.
In this example the break-even time is approximately 36.5 days. If the borrower expects to keep the debt for another year, refinancing may make economic sense before considering risk. If only ten days remain, it likely does not.
DN DeFi Borrowing True APR Calculator
The calculator below models a borrowing strategy using your own assumptions. It estimates a time-weighted borrowing rate, incentive-adjusted debt APR, friction APR, collateral opportunity carry, broader strategy APR and refinance break-even period.
DeFi Borrowing True APR Calculator
Estimate the annualized economic cost of a collateralized DeFi loan after rate changes, incentives, transaction friction and collateral opportunity cost.
Loan
Borrow Incentives
Collateral Economics
Transaction & Refinance Friction
DN Borrow Analysis
True Debt APR describes the liability itself. True Strategy APR adds the economic effect of placing collateral in the borrowing strategy.
The tool uses simple annualized rates rather than attempting to replicate every protocol's exact compounding implementation. It is intended for comparison and scenario analysis, not precise debt accounting.
How to Use the Calculator Correctly
The distinction between yield earned here and alternative collateral yield is important.
If your collateral earns 2% in the borrowing protocol and you believe its relevant alternative yield is also 2%, enter 2% and 2%. Opportunity carry becomes zero.
If posted collateral earns 0% but you believe the same asset would otherwise earn 3% under a comparable risk profile, enter 0% and 3%. The opportunity cost is then included.
Neither number is a recommendation. The user defines the relevant alternative.
Incentives Should Be Haircut, Not Worshipped
Suppose a market shows a 9% borrow APR and 8% rewards, suggesting a 1% net cost. That can be useful, but DN also wants to show the 9% gross debt APR, reward asset, reward duration, realization assumption and the fact that debt can still grow at the underlying rate.
The calculator therefore lets readers apply a Reward Realization Factor rather than blindly counting every advertised reward dollar at 100 cents.
Different Borrowers Need Different Answers
| Borrower Type | Main Objective | Primary DN Metric |
|---|---|---|
| Liquidity borrower | Borrow stablecoins without selling BTC/ETH | True Debt APR + liquidation headroom |
| Leveraged yield farmer | Earn more on deployment than debt costs | Borrow Spread |
| Looping strategy | Increase exposure through recursive borrowing | Carry Reversal Threshold + liquidation sensitivity |
| Treasury borrower | Predictable funding cost | Rate stability + refinance friction |
DN Borrow Spread
If a downstream strategy yields 9% and True Debt APR is 6%, the gross spread is 3%. If strategy yield later falls to 5% while borrowing rises to 9%, the spread becomes −4%.
DN Carry Reversal Threshold
This is the borrowing rate at which an otherwise positive-carry strategy stops producing positive carry after other costs. It is a natural candidate for a future DN monitoring alert.
DN Borrowing True APR Benchmark
The live version of this Index should move beyond one-time interface snapshots. Every future benchmark observation should record enough information to reconstruct what a borrower actually experienced through time.
Fields DN Should Record
| Category | Fields |
|---|---|
| Market identity | Protocol, network, collateral, debt asset, UTC timestamp |
| Rate state | Borrow APR, borrow APY, utilization, IRM parameters, borrower incentives, reward asset |
| Collateral | Collateral supply yield, LTV/LLTV, liquidation threshold, health factor |
| Friction | Gas to enter, gas to exit, claim cost, refinancing cost |
| Rate history | 7-day realized average APR, 30-day realized average APR, 90-day realized average APR, P95 APR, time above target APR |
| Outcome metrics | Debt growth, rate-shock persistence, True Debt APR, True Strategy APR |
The First Benchmark Cohort
The cleanest first study uses USDC debt and standardized collateral cohorts rather than mixing incomparable markets.
- Collateral: ETH/WETH, wstETH and cbBTC/WBTC.
- Networks: Ethereum first, then Base and Arbitrum.
- Protocols: Aave, Morpho, Compound and Venus where a sufficiently comparable market exists.
- Borrow sizes: $10,000 for gas-sensitive retail economics, $100,000 for HNW/active DeFi, and $1 million for professional/institutional borrowing.
The Future DN Leaderboard
| Protocol / Market | Current APR | 30d Realized | P95 APR | Rewards | Collateral Carry | Friction APR | True Strategy APR |
|---|---|---|---|---|---|---|---|
| Aave ETH/USDC | Live data | Live | Live | Live | Live | Live | Calculated |
| Morpho ETH/USDC | Live data | Live | Live | Live | Live | Live | Calculated |
| Compound ETH/USDC | Live data | Live | Live | Live | Live | Live | Calculated |
| Venus comparable market | Live data | Live | Live | Live | Live | Live | Calculated |
DN should not populate this table with one-day snapshots and call it a historical ranking. The purpose of the live dataset is to measure the rate path borrowers actually experience.
DN Citation-to-Conversion Methodology
DN-BTA v1.0 is designed to compare the economics of collateralized DeFi borrowing without pretending a single displayed rate captures the entire strategy.
- True Debt APR measures the liability layer.
- True Strategy APR adds collateral opportunity carry.
- Friction APR annualizes entry, exit and origination costs across the intended holding period.
- Rewards are separated from debt accrual and can be haircut using a realization factor.
- Rate shocks are modelled using the percentage of the holding period expected at a stress rate.
- Liquidation risk is not converted into fake APR. It remains a separate risk dimension.
- Commercial relationships contribute zero points to methodology.
Future DN Live Dataset
The first empirical cohort should standardize USDC debt against ETH/WETH, wstETH and cbBTC/WBTC collateral, beginning on Ethereum before expanding to Base and Arbitrum.
DN should collect current APR, utilization, IRM parameters, incentives, collateral yield, health factors, gas costs, 7-day/30-day/90-day realized rates, P95 APR, time above stress levels and refinancing costs at $10,000, $100,000 and $1 million debt sizes.
What Would Prove the DN Thesis Wrong?
The framework becomes less valuable if live evidence shows that starting APR predicts realized borrowing cost extremely well, fixed transaction friction is negligible for almost all practical loan sizes, collateral treatment is economically similar across major protocols, incentives are reliably realized at headline rates, and borrowers almost never need to refinance.
If the data shows that, DN should publish it. The methodology exists to test the thesis, not protect it.
The Bottom Line
The APR shown when a DeFi loan opens is a snapshot, not a promise.
A borrower ultimately experiences a path:
starting rate → utilization changes → rate shocks → incentives → collateral carry → transaction friction → possible refinancing → debt growth → repayment
The DN framework therefore replaces the question “What is the cheapest borrowing APY today?” with a more decision-useful question:
“What did this borrowing strategy actually cost over the period capital was deployed?”
The core DN metrics are True Debt APR, True Strategy APR, Friction APR, Collateral Opportunity Carry, Borrow Rate Volatility, Rate Shock Exposure, Rate Shock Persistence, Debt-to-Liquidation Drift, Refinance Break-Even Days and Carry Reversal Threshold.
Need a Platform Before Moving Onchain?
DN does not currently use a lending affiliate relationship to influence this benchmark. If you need a centralized venue to acquire eligible collateral or stablecoins before moving assets onchain, independently verify withdrawal networks, fees and jurisdiction availability.
Explore BitgetPartner code: nqef. This is not a DeFi lending recommendation and does not affect the protocols assessed above.
Primary Sources & Evidence
- Aave: Borrow Tokens — utilization-sensitive borrowing mechanics.
- Aave: Supply Tokens — supplied assets and collateral yield.
- Aave: Liquidations — Health Factor and liquidation mechanics.
- Aave Governance: 16 Sep 2026 IRM / cap changes — evidence that interest-rate curves remain actively managed.
- Morpho: Borrow — Get Started — collateral treatment in variable-rate markets.
- Morpho: Interest Rates — AdaptiveCurveIRM and utilization.
- Morpho: Rewards — net borrow APY and borrower incentive treatment.
- Morpho: Liquidation — debt growth and liquidation mechanics.
- Compound III: Interest Rates — base-asset utilization curves and non-yielding collateral.
- Compound III: Collateral & Borrowing — collateral and borrowing architecture.
- Compound III: Liquidation — liquidation collateral factors.
- Venus: Liquidation Guide — collateral factor and liquidation threshold framework.
Frequently Asked Questions
What is the real cost of borrowing on Aave?
It depends on the realized variable borrow rate, holding period, transaction costs and collateral economics. Aave states that borrowing rates change dynamically with utilization and that supplied collateral can continue earning supply interest.
Is Morpho cheaper than Aave for borrowing?
Not universally. Morpho can offer competitive isolated-market rates and borrower incentives, but its variable-rate market collateral does not natively earn yield. Aave collateral generally can. The relevant comparison is therefore market- and strategy-specific.
Does Compound collateral earn interest?
Compound III documentation states that collateral assets do not earn interest. Only a positive supplied balance of the market's base asset earns supply interest.
Can my DeFi borrow rate change after I borrow?
Yes on variable-rate markets. Aave, Morpho, Compound III and Venus all use borrowing-rate mechanisms that respond in some form to utilization or protocol rate parameters.
Can borrowing interest cause liquidation even if collateral price does not fall?
Yes. Debt can grow as interest accrues, worsening LTV or Health Factor. Morpho explicitly identifies accrued debt growth as a potential liquidation path.
What does negative borrow APY mean?
It generally means borrower incentives exceed the displayed borrowing rate on an annualized economic basis. It does not necessarily mean the debt balance shrinks. On Morpho, for example, debt can still increase even if rewards make net APY negative.
Should borrower rewards be deducted from APR?
They can be shown as an economic offset, but DN recommends displaying both gross debt APR and incentive-adjusted cost so users can distinguish actual debt accrual from token rewards.
What is DN True Strategy APR?
It is DN's estimate of the borrowing strategy's annualized economic cost after the realized debt rate, incentives, fixed transaction friction and collateral opportunity carry are considered.