“95% win rate” sounds like evidence of an extraordinary trading system. It may instead describe a strategy that wins tiny amounts repeatedly, hides open losses, averages down aggressively or was optimized on historical data. DN breaks the headline number apart and shows the ten questions that matter more than win rate alone.
What Matters
A high win rate is not the same thing as a profitable trading system. The missing variables are usually the size of the wins, the size of the losses, the number of trades, unrealized positions, drawdown, trading costs and whether the result came from live trading at all.
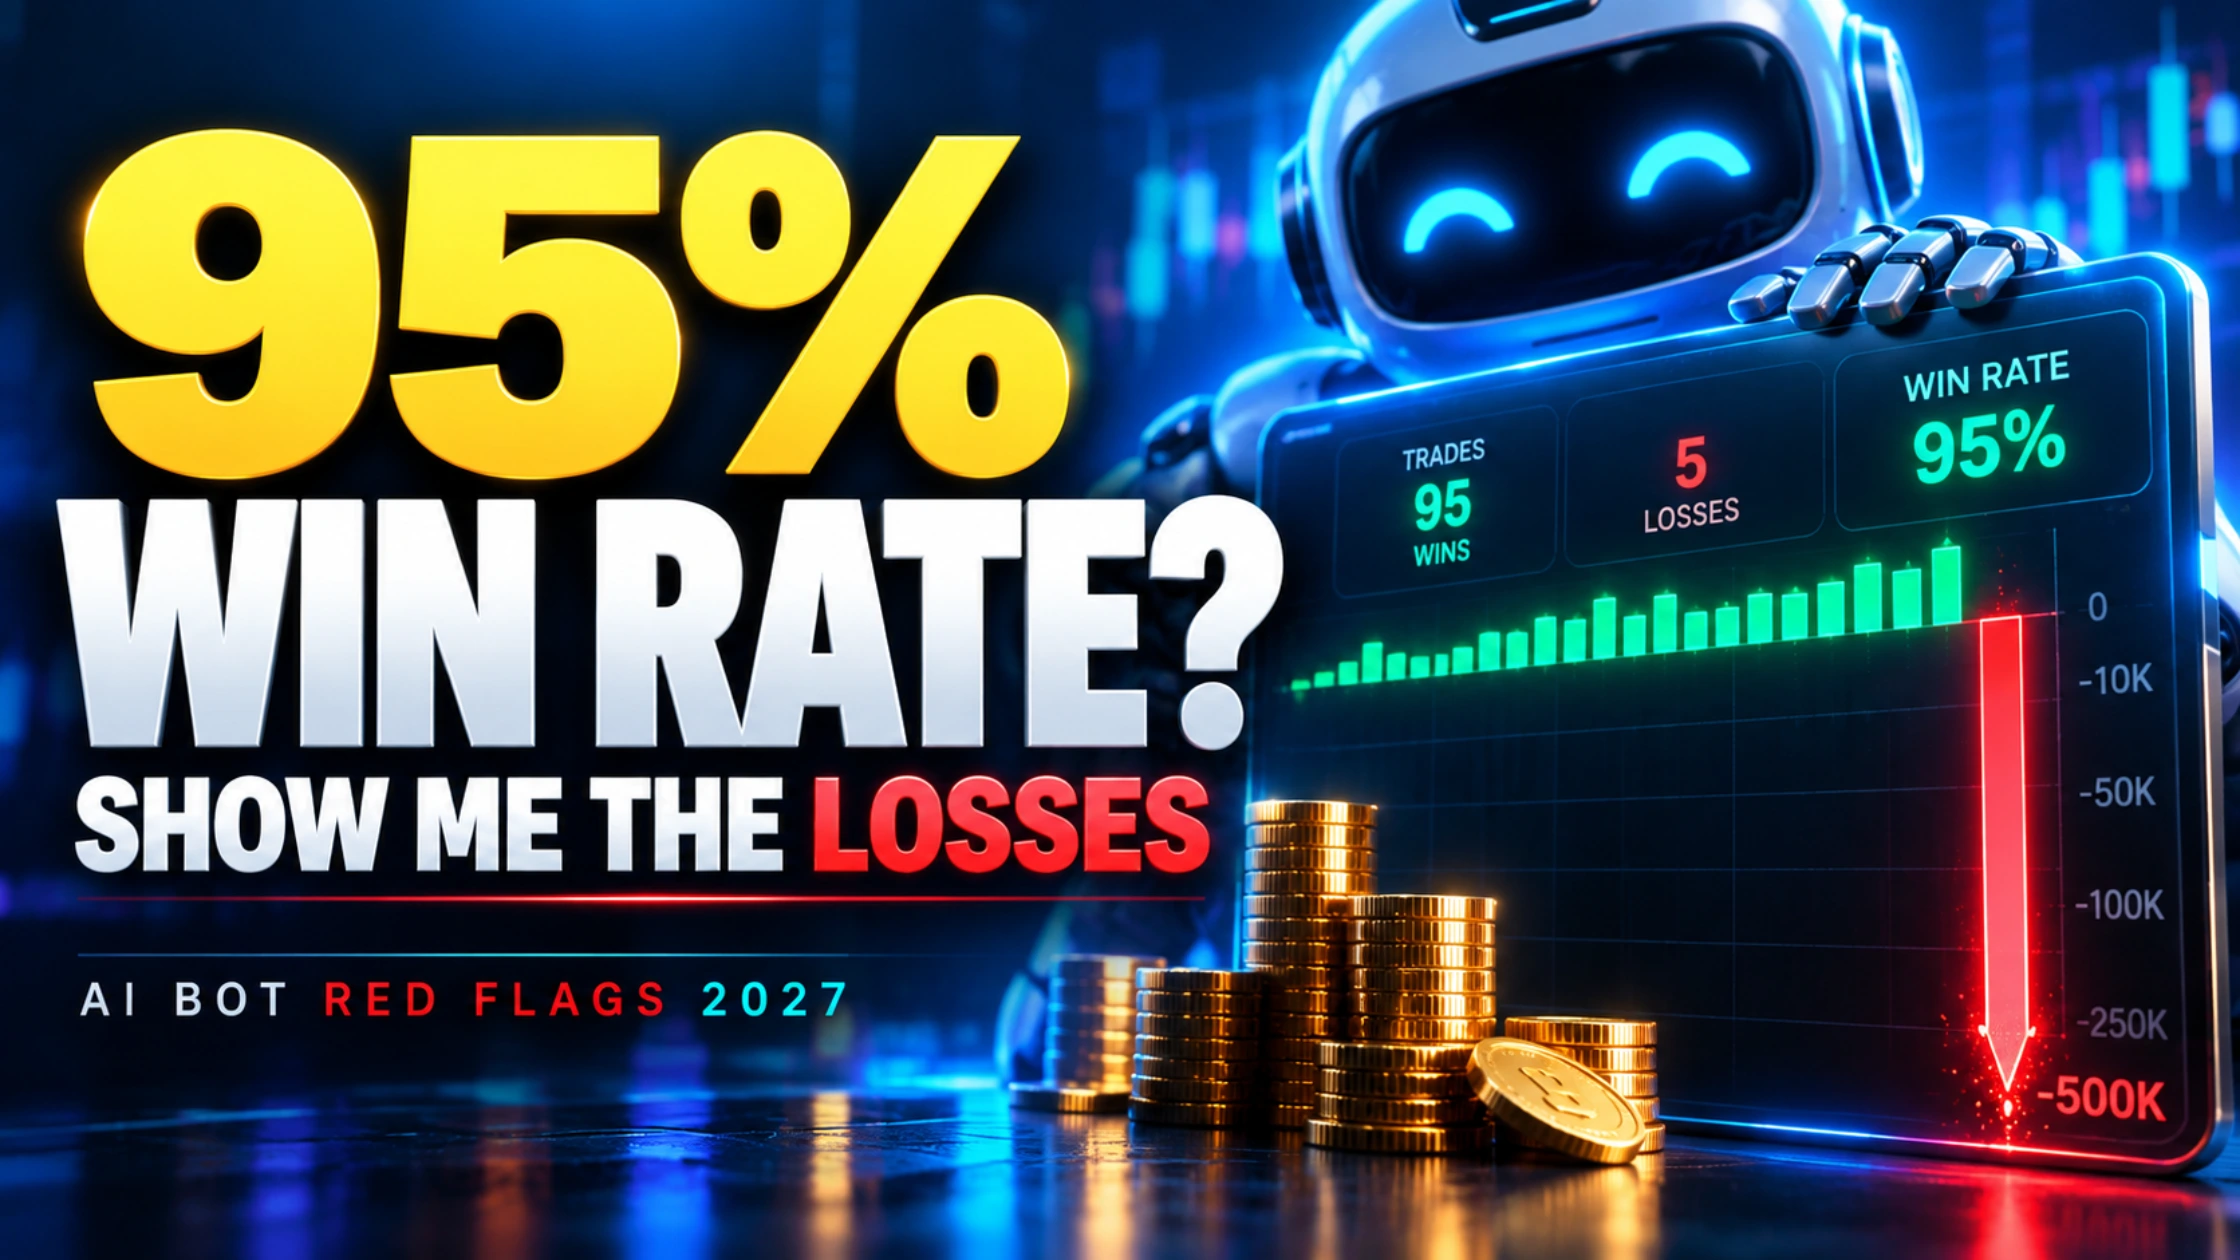
- A 95% win rate can lose money. If the average winner makes 0.25% while the average loser loses 6%, the five losing trades in every 100 can outweigh the 95 winners before fees.
- Win rate without payoff ratio is incomplete. You need average win divided by average loss.
- Closed trades can hide open losses. A strategy may show dozens of profitable closed positions while one deeply underwater position remains unresolved.
- Martingale and aggressive averaging-down systems can manufacture attractive win rates for long periods. Their risk may be concentrated in rare but extremely large losses.
- Maximum drawdown often tells you more about survivability than win rate.
- Backtested or simulated win rates are not live win rates. The SEC has explicitly noted that backtested performance can be optimized through hindsight.
- Gross win rate ignores economic friction. Fees, spread, slippage, funding and subscription costs can turn marginally positive expectancy negative.
- Sample size matters. Winning 19 of 20 trades is different evidence from winning 950 of 1,000 across multiple market regimes.
- Leverage and position sizing can dominate the headline statistic. A system can win frequently while one leveraged loss erases months of small profits.
- “AI” does not validate the number. The CFTC explicitly warns that fraudsters promote AI trading systems using enormous return claims and even supposed 100% win rates.
DN Evidence Block
- Verification date: 15 October 2026.
- Core question: what mathematical and evidentiary information is missing when an AI trading advertisement promotes a headline win rate?
- Regulatory evidence: CFTC AI-trading-bot advisory, Investor.gov AI-fraud guidance and SEC investment-adviser marketing guidance.
- Current enforcement context: September 2026 SEC complaints included allegations involving fictitious AI-bot profits and, in one case, AI trading bots that allegedly did not exist.
- Performance framework: win rate, payoff ratio, expectancy, drawdown, open-position treatment, sample size, leverage and net costs.
- Primary distinction: frequency of winning trades is not the same thing as magnitude of profit.
- DN proprietary tools: Win-Rate Mirage Test and Win-Rate Reality Calculator.
- Not a platform ranking: this article evaluates advertising and performance evidence rather than recommending a specific trading system.
The CFTC warns that scammers use interest in artificial intelligence to promote trading bots and signal systems claiming unusually high or guaranteed returns. Its AI trading advisory specifically references claims of enormous returns and even 100% “win” rates, while emphasizing that AI cannot predict sudden market changes.
The SEC's September 29, 2026 enforcement announcement provides an even more recent example of why performance displays require verification. In one alleged scheme, the SEC says supposed AI trading bots did not exist and investor funds were never used to earn the represented returns.
The 95% Win-Rate Illusion
Imagine two trading bots.
Bot A wins 95% of its trades.
Bot B wins 55%.
Which is better?
There is no responsible answer yet.
Suppose Bot A wins an average of:
0.25%
but loses:
6%
on the average losing trade.
Across 100 trades:
95 wins × 0.25% = +23.75%
5 losses × 6% = -30%
Before fees, the simplified total is already:
-6.25%.
The advertisement can still truthfully say:
95% WIN RATE.
The Metric That Should Sit Beside Every Win Rate
The missing calculation is trade expectancy.
A simplified version is:
Expected return per trade = (Win probability × Average win) - (Loss probability × Average loss) - Average trading friction
A strategy can therefore have:
- a low win rate and positive expectancy,
- a high win rate and positive expectancy,
- a low win rate and negative expectancy,
- or a high win rate and negative expectancy.
The win percentage alone cannot tell you which one you are looking at.
The Win-Rate Mirage occurs when the frequency of profitable trades creates the appearance of a strong strategy while loss severity, unresolved exposure or trading friction makes the underlying economics weak or negative.
The 10 Red Flags Hidden Behind “95% Win Rate” Ads
No Average Win and Average Loss
This is the first number to demand.
If an advertisement says:
“95% winning trades”
but does not show how much each winning and losing trade makes or loses, the statistic is incomplete.
A 95% win rate can survive extremely poor economics if each losing trade is sufficiently large.
DN calls the relationship:
Loss Severity Ratio.
It is:
Average loss ÷ Average win
If the average loss is 20 times the average win, each losing trade requires roughly twenty average winners to recover before costs.
No Trade Count or Sample Size
A percentage without a denominator can create false precision.
“95% win rate” could mean:
19 wins from 20 trades.
Or:
9,500 wins from 10,000 trades.
Those represent very different amounts of evidence.
Even a large sample can still be misleading if every trade occurred during the same unusual market regime.
Ask:
- How many trades?
- Across how many months or years?
- Across which markets?
- Across which volatility regimes?
Open Losing Positions Are Missing
A system can maintain an excellent closed-trade win rate simply by refusing to close losing positions.
Imagine:
- 95 profitable trades are closed,
- three modest losers are closed,
- and two enormous losing positions remain open.
A marketing dashboard may emphasize the closed trades.
The portfolio may tell a completely different story.
This is especially important with:
- Grid systems,
- DCA bots,
- martingale variants,
- averaging-down strategies,
- and systems that hold until recovery.
DN calls the distortion:
Closed-Trade Bias.
The Strategy Keeps Increasing Size After Losses
A martingale-style strategy can create a long sequence of apparent wins.
After a loss, it increases exposure.
If the market eventually reverses, the recovery trade can erase earlier losses and the sequence may be recorded as a success.
Until the reversal does not arrive quickly enough.
Then exposure can grow rapidly.
The important question becomes:
How much capital must remain available for the recovery ladder to survive?
DN calls this:
Recovery Dependency.
A strategy has high Recovery Dependency when its impressive win rate depends on having enough capital, margin or time to keep adding exposure until the market eventually returns.
Maximum Drawdown Is Nowhere to Be Found
Win rate counts outcomes.
Drawdown measures pain.
A strategy may ultimately close a trade profitably after spending weeks at:
-35% unrealized loss.
The final record may count:
one win.
The user experienced:
a 35% decline in equity.
That difference matters because a system can fail through:
- margin exhaustion,
- liquidation,
- capital withdrawal,
- risk-limit breach,
- or user capitulation
before the theoretical recovery arrives.
The “Track Record” Is Actually a Backtest or Demo
A backtest can be useful.
It is hypothetical performance.
The SEC has explicitly noted that backtested performance can be misleading because strategy parameters can be adjusted after historical outcomes are already known.
That creates hindsight optimization.
The strategy can be tuned repeatedly until history looks impressive.
Real trading adds:
- latency,
- slippage,
- partial fills,
- spread changes,
- liquidity limits,
- funding,
- exchange failures,
- and actual capital constraints.
Paper performance should therefore be labelled as paper performance.
The Advertised Period Was Cherry-Picked
A bot may have a 95% win rate:
during a bull market.
Or:
during one month.
Or:
on one asset.
Or:
after the strategy was repeatedly optimized until a favorable historical window appeared.
That does not tell you how the system behaves through:
- trend reversals,
- volatility shocks,
- long sideways periods,
- liquidity crises,
- or structural regime changes.
The SEC's marketing framework provides a useful general principle here: performance presentations should not selectively include or exclude results in a manner that creates a misleading impression.
Costs Are Missing From the Result
Very high win-rate strategies often target relatively small price movements.
That makes trading friction particularly important.
A strategy capturing:
0.20%
per winning trade can look attractive before:
- maker/taker fees,
- spread,
- slippage,
- funding,
- borrow costs,
- subscription fees,
- model/API fees,
- and taxes where applicable.
The CFTC specifically tells investors evaluating AI trading systems to consider fees, spreads and subscription costs.
For high-turnover bots, small costs repeat.
Repeated friction can destroy a small statistical edge.
Leverage and Position Size Are Hidden
Two strategies can share the same win rate and produce completely different portfolio risk.
A bot using:
1% of the account per trade
does not have the same failure profile as one using:
20% of the account at 10x leverage.
Win rate says nothing about:
- position concentration,
- notional exposure,
- margin utilization,
- liquidation distance,
- or correlated simultaneous positions.
DN calls the missing dimension:
Loss Capacity.
Loss Capacity asks how many ordinary losing events the portfolio can absorb before the strategy is forced to stop.
“AI” Is Presented as Proof the Win Rate Is Credible
Artificial intelligence is a technology description.
It is not performance evidence.
A trading product may use:
- machine learning,
- LLMs,
- optimization,
- signal classification,
- agentic tool use,
- or ordinary deterministic algorithms.
None of those facts independently validates:
95%.
The CFTC specifically warns that AI hype is being used to market automated trading systems with implausibly high returns and purported 100% win rates.
And in September 2026, the SEC alleged that one investment scheme promoted AI trading bots that did not exist at all.
The correct evidence chain is:
documented technology → reconstructable trades → net economic outcome.
Not:
AI label → assumed superior performance.
The DN Win-Rate Mirage Test
A headline win rate becomes much more meaningful when it is paired with four additional variables.
| Metric | What it answers | Why it matters |
|---|---|---|
| Win Rate | How frequently did trades finish positive? | Frequency only |
| Payoff Ratio | How large are wins relative to losses? | Shows whether losses overwhelm winners |
| Expectancy | What is the average economic outcome per trade? | Combines frequency and magnitude |
| Maximum Drawdown | How bad did the equity decline become? | Measures survivability |
| Net Friction | How much does trading cost? | Separates gross edge from usable edge |
The Break-Even Win Rate
Suppose the average winning trade earns:
1%
and the average losing trade loses:
1%.
Ignoring costs, the strategy needs to win around half the time to break even.
But suppose:
average winner = 0.25%
average loser = 5%
Now the required win rate rises dramatically.
The correct win-rate target therefore depends on payoff structure.
A headline percentage cannot be evaluated independently from the average loss.
For highly asymmetric strategies, a rare losing event can contribute more to long-term economics than dozens of ordinary winning trades. The larger the Loss Severity Ratio, the less useful headline win rate becomes as a standalone performance measure.
DN Win-Rate Reality Calculator
Enter a headline win rate and the missing economics.
Win-Rate Reality Calculator
See whether a high win rate still produces positive simplified expectancy after average losses and trading friction are included.
Win-Rate Mirage
Why Martingale Systems Can Look Brilliant Until They Don't
The most important danger of win-rate marketing is that the attractive statistic can be produced by the structure of the strategy itself.
Suppose a bot buys.
Price falls.
It buys more.
Price falls again.
It buys more again.
Each new entry lowers the average cost.
When price eventually rebounds, the combined position may close with a small profit.
The entire sequence can be counted as:
one winning trade.
This can produce impressive historical win percentages.
The real risk appears when the market keeps trending in the wrong direction long enough to exhaust:
- available capital,
- margin,
- configured safety orders,
- or liquidation distance.
The eventual loss can be enormous relative to dozens of earlier wins.
The Survival-Adjusted Question
Instead of asking:
“How often does the bot win?”
ask:
“What market path causes the bot to stop surviving?”
DN calls this:
Survival-Adjusted Performance.
A strategy is only useful if the capital survives long enough for the statistical edge to continue operating.
That means performance analysis should include:
- worst historical drawdown,
- worst losing streak,
- worst single-trade loss,
- largest simultaneous exposure,
- maximum margin utilization,
- and the assumptions required for recovery.
A 60% Win Rate Can Be Better Than 95%
Consider another simplified strategy:
- 60% win rate,
- average win = 2%,
- average loss = 1%.
Its simplified pre-cost expectancy is:
0.60 × 2%
minus
0.40 × 1%
which equals:
+0.80% per trade.
Now compare a strategy with:
- 95% wins,
- average win = 0.25%,
- average loss = 6%.
The headline number looks dramatically better.
The economics are dramatically worse.
This is why sophisticated traders often care more about:
- expectancy,
- profit factor,
- drawdown,
- risk-adjusted return,
- and portfolio survival
than raw percentage of winning trades.
Gross Performance vs Net Performance
Another common distortion is showing the strategy before costs.
The SEC's investment-adviser marketing framework provides a useful benchmark: where covered advisers advertise gross performance, corresponding net performance is generally required under the rule.
AI trading software is not automatically subject to that rule merely because it displays bot statistics.
But the analytical principle is valuable.
If an advertisement tells you how the strategy performs before costs while you will experience performance after costs, the displayed number is not the number you care about.
Why Tiny Profit Targets Create Great-Looking Dashboards
Suppose a bot takes profit whenever a position gains:
0.15%.
It has a wide stop or no hard stop.
In quiet markets, the strategy can repeatedly accumulate tiny wins.
The dashboard looks extraordinary.
Green.
Green.
Green.
Green.
Then one extreme move creates:
-12%.
That one trade equals eighty average 0.15% winners before friction.
The key statistic was never the win rate.
It was the asymmetry.
Five Numbers DN Would Rather See Than “95%”
| Metric | Why DN wants it |
|---|---|
| Net expectancy per trade | Shows average economic value after frequency, magnitude and costs |
| Maximum equity drawdown | Shows how much capital declined before recovery |
| Profit factor | Compares gross winning amount with gross losing amount |
| Worst trade / worst sequence | Exposes tail risk hidden by averages |
| Live trade count across regimes | Shows how much real-world evidence exists |
The “One Bad Trade” Test
An easy way to challenge a high-win-rate system is:
How many normal winners does one normal loser erase?
If:
average winner = 0.2%
average loser = 4%
then:
one loss erases approximately:
20 average winners.
The strategy may still be good if losses are sufficiently rare.
But now the 95% headline has useful context.
Five losing trades per 100 could erase the equivalent of one hundred average winners.
DN defines the Recovery Multiple as the number of average winning trades required to recover one average losing trade. High-win-rate advertisements become increasingly fragile as the Recovery Multiple rises.
What a Better AI Trading Performance Card Would Show
Instead of:
WIN RATE: 95%
DN would rather see:
| Field | Example |
|---|---|
| Live / backtest / demo | Live |
| Trading period | Jan 2025 to Sep 2026 |
| Total trades | 1,284 |
| Win rate | 61.2% |
| Average win | 1.4% |
| Average loss | 0.9% |
| Net expectancy | Disclosed after trading costs |
| Maximum drawdown | Disclosed |
| Worst trade | Disclosed |
| Open losing positions included? | Yes |
| Leverage | 0x / 1x / disclosed |
| Fee model | Documented |
| Underlying trade records | Reconstructable |
The precise numbers matter less than the completeness of the picture.
Safer Ways to Test an AI Trading Idea
The alternative to believing an advertisement is to reproduce the strategy behavior yourself.
Start with:
paper or demo trading.
Coinrule currently offers paper workflows and explicitly separates MCP Read Only from Read + Write permissions. A Read Only assistant can inspect supported information without gaining write tools.
Test With CoinruleAffiliate link. Paper results remain simulations and should not be treated as proof of live profitability.
3Commas also currently provides Demo Trading using virtual assets and real market-data feeds, allowing users to observe automation before connecting real capital.
Explore 3Commas Demo TradingAffiliate link. Demo trading does not reproduce all live execution conditions.
What DN Would Verify Before Believing 95%
The minimum evidence pack should include:
- exact trading period,
- live vs demo vs backtest classification,
- total number of trades,
- complete open and closed positions,
- average and median win,
- average and median loss,
- profit factor,
- maximum drawdown,
- worst trade,
- longest losing streak,
- position-sizing methodology,
- leverage,
- all costs,
- and enough raw trade information to reconstruct the result.
If those numbers are unavailable, the headline win rate should be treated as advertising rather than a complete performance record.
The 95% Claim Compression Problem
A single number can compress a large amount of hidden information.
DN calls this:
Claim Compression.
“95% win rate” compresses:
- 95 wins,
- five losses,
- their individual sizes,
- their sequence,
- the time spent underwater,
- open positions,
- leverage,
- fees,
- market regimes,
- capital allocation,
- and whether the trades were real.
The marketing becomes easier to understand precisely because the risk information disappears.
The most persuasive financial metrics are often those that compress complicated distributions into one memorable number. Due diligence reverses that compression by reconstructing the losses, costs, assumptions and unresolved exposures hidden behind the headline.
A Better Rule for Evaluating AI Trading Ads
Do not ask:
“Is 95% impressive?”
Ask:
“What distribution of wins, losses and costs produced 95%?”
Then ask:
“Could the portfolio survive the path required to produce those results?”
Those two questions eliminate much of the marketing advantage of a headline percentage.
Limitations
- Win rate can still be useful. DN is not arguing that win percentage is irrelevant, only that it is insufficient alone.
- Expectancy estimates depend on averages. Real return distributions can be highly skewed and nonlinear.
- The DN calculator is simplified. It does not simulate compounding, liquidation, changing position size, correlations or overlapping positions.
- Backtests are not inherently deceptive. They are valuable research tools when their hypothetical nature, assumptions and limitations are clearly disclosed.
- High win-rate strategies are not automatically bad. Some legitimate strategies can have high win rates while maintaining positive expectancy and controlled tail risk.
- Low win-rate strategies are not automatically good. Large theoretical winners do not help if the strategy cannot survive its losing periods.
- Regulatory rules vary. References to SEC adviser-marketing rules are presented as useful performance-disclosure benchmarks and should not be interpreted as saying every trading-bot vendor is subject to those rules.
- Recent enforcement complaints contain allegations. Allegations are not final judicial findings unless and until adjudicated.
What Would Prove the Headline Wrong?
DN favors a falsification question for every high-performance claim.
For a 95% win-rate claim, ask:
What evidence would cause us to stop believing that 95% represents an economically attractive live strategy?
Examples include:
- negative expectancy after costs,
- one loss erasing dozens of winners,
- deep unresolved losing positions,
- extreme martingale exposure,
- unreported drawdowns,
- a result that exists only in a backtest,
- a short cherry-picked sample,
- or trade records that cannot be reconstructed.
A claim becomes more credible when the advertiser makes it easy to test how it could be wrong.
The Bottom Line
A 95% win rate is not automatically impressive.
It is incomplete.
You still need:
the size of the wins,
the size of the losses,
the number of trades,
the drawdown,
the open positions,
the leverage,
the costs,
and evidence that the trading actually happened.
A bot winning nineteen trades out of twenty can still be a terrible trading system.
A strategy winning slightly more than half its trades can still have excellent economics.
The percentage is therefore not the verdict.
It is the beginning of the investigation.
And when an AI trading advertisement leads with:
95% WIN RATE
the first question should not be:
“Where do I deposit?”
It should be:
“Show me the losses.”
This article is the quantitative companion to DN's broader pre-deposit AI Trading Claim Verifier. It focuses specifically on performance advertisements built around unusually high win rates.
DN evaluates ten hidden variables: Payoff Ratio, Sample Size, Closed-Trade Bias, Recovery Dependency, Drawdown, Live-vs-Hypothetical Status, Period Selection, Trading Friction, Position / Leverage Risk and AI Performance Evidence.
Proprietary DN concepts introduced or extended here include: Win-Rate Mirage, Loss Severity Ratio, Closed-Trade Bias, Recovery Dependency, Loss Capacity, Survival-Adjusted Performance, Recovery Multiple and Claim Compression.
The DN Win-Rate Reality Calculator uses simplified expectancy arithmetic to expose whether the headline percentage remains economically plausible after average losses and estimated friction.
Commercial relationships contribute zero points and do not change the evidence standard applied to performance claims.
Primary Sources & Evidence
- CFTC, AI Won't Turn Trading Bots into Money Machines
- Investor.gov, Artificial Intelligence and Investment Fraud
- Investor.gov, Protect Your Money: How to Avoid Investment Scams
- SEC, Investment Adviser Marketing
- SEC, Investment Adviser Marketing Final Rule, discussion of hypothetical and backtested performance
- SEC, September 29, 2026 AI Trading Bot Fraud Allegations
- Coinrule, MCP Permissions and Security Explained
- 3Commas, Demo Trading Guide, August 2026
Frequently Asked Questions
Is a 95% win rate good for a trading bot?
Not necessarily. Win rate only describes how frequently trades finish profitably. A 95% win-rate strategy can still lose money if the average losing trade is much larger than the average winning trade or if fees and other costs consume the edge.
Can a trading bot have a 95% win rate and still lose money?
Yes. For example, if 95 trades gain an average 0.25% while five trades lose an average 6%, the simplified result is negative even before trading costs.
What matters more than win rate?
Important complementary metrics include payoff ratio, trade expectancy, maximum drawdown, profit factor, worst trade, sample size, leverage, trading costs and whether the performance came from live trading.
What is trading expectancy?
Expectancy estimates the average economic outcome of a trade by combining the probability and size of winning and losing trades, usually after accounting for relevant trading friction.
What is the DN Win-Rate Mirage?
The Win-Rate Mirage describes a strategy that appears attractive because it wins frequently while large losses, hidden open exposure or trading friction make its underlying economics much weaker than the headline percentage suggests.
Why can martingale bots have very high win rates?
Martingale-style systems can increase exposure after losses and wait for price recovery. This may create many profitable completed sequences, but rare extended adverse moves can create disproportionately large losses or liquidation risk.
What is Closed-Trade Bias?
Closed-Trade Bias occurs when a performance statistic emphasizes completed profitable trades while large unresolved losing positions remain open and are not reflected adequately in the headline result.
What is the Recovery Multiple?
The Recovery Multiple is the number of average winning trades required to recover one average losing trade. It is calculated approximately as average loss divided by average win.
Are backtested win rates trustworthy?
Backtests can be useful research tools but they are hypothetical. Results can be affected by hindsight optimization, parameter selection, fees, slippage assumptions, liquidity and the chosen historical period.
Does AI make a high win-rate claim more credible?
No. Artificial intelligence describes technology, not verified performance. The win-rate claim still needs reconstructable trade evidence, methodology, loss data, costs and appropriate risk metrics.
What should I ask when an AI bot claims a 95% win rate?
Ask for the number of trades, average win, average loss, maximum drawdown, worst trade, open positions, leverage, fees, test period and evidence showing whether the results came from live trading rather than a backtest or demo.
Freshness, Change Log & Corrections
| Date | Change |
|---|---|
| 15 October 2026 | Initial edition published as the quantitative companion to DN's broader AI Trading Claim Verifier. |
| 15 October 2026 | Verified current CFTC AI-trading-bot guidance concerning extraordinary returns and purported 100% win rates. |
| 15 October 2026 | Reviewed SEC guidance concerning selective, hypothetical and backtested performance presentations. |
| 15 October 2026 | Added DN Win-Rate Mirage, Loss Severity Ratio, Closed-Trade Bias, Recovery Dependency, Loss Capacity, Survival-Adjusted Performance, Recovery Multiple and Claim Compression. |
| 15 October 2026 | Added DN Win-Rate Reality Calculator. |
| 15 October 2026 | Verified current Coinrule permission documentation and 3Commas Demo Trading documentation for lower-risk experimentation pathways. |
Last verified: 15 October 2026.
Correction policy: performance claims, product functionality and regulatory guidance change. DN will update this article when material evidence, regulatory actions or trading-platform methodologies change.
Readers and companies can submit factual corrections through the Decentralised News Contact page. Commercial relationships do not prevent corrections, negative findings or removal.